

 Facebook
 X
 Pinterest
 Copy Link
Here’s Where To Start if You’re Selling and Buying at the Same Time

If you’re a homeowner getting ready to move, one question usually comes first: should you buy your next home before you sell, or sell your current house before you start looking?
There’s no single right answer. The best call depends on your finances, your local market, and your timeline. And a trusted agent can help you weigh all of it.
But in a lot of cases these days, selling first puts you in the stronger spot.
The Advantages of Selling First
Selling is usually the trickier half of a move today, so getting it done first clears your biggest hurdle. And that’s especially true right now, because there are more homes for sale than there are buyers, which means houses are taking longer to sell than they did a year or two ago.
So how does leading with your sale pay off? Let’s start with the money.
- You Won’t Get Stuck Paying Two Mortgages
Buy before you sell, and you could end up carrying two mortgages at once. And especially since houses are staying on the market longer these days, that overlap may drag on for more time than you’d planned. And if unexpected repairs come up, it could get even more expensive.
Selling first takes that risk off the table, so you’re not multitasking homeownership. As Ramsey Solutions puts it:
“It’s best to sell your old home before buying a new one to avoid unnecessary risks and possible headaches.”
- You Can Use Your Equity To Fuel Your Move
This is always true, but one of the biggest perks of selling first is that you’ll know exactly how much money you’re walking away with. And one of the big figures that matters in that conversation is how much equity you have in your current place.
Equity is basically your house’s value minus what you still owe on your mortgage. And it adds up fast. According to Realtor.com, homeowners who’ve been in their home for 5 years have about $180,000 in equity on average. And those who’ve had their home for 6-10 years? They have over $340,000.
After you sell, you can use that money to cover your down payment or even buy your next home in cash. And knowing that profit up front helps you plan your next move.
- Your Offer Will Be Hard To Pass Up
When your house is already sold, you don’t have to make your offer contingent on that sale. In a market where buyers are taking their time, that’s exactly what a seller wants to see.
Picture it from the seller’s side. If their house has been sitting for a while, they’ll gravitate toward the offer most likely to close without a snag.
That can also give you room to ask for a little more, like repairs, since a motivated seller would rather keep things moving than lose you and wait for another offer to come in. Your agent can help you make the most of your upper hand in that scenario.
Is There a Catch?
Selling first has its tradeoffs too, and it helps to see the pros and cons side by side before you decide. Here’s a quick breakdown based on information from Zillow (see visual below):

The cons are manageable with the right plan, so talk about them with your agent. They can help you negotiate things like a rent-back, where you stay in your house for a set time after closing, or line up flexible closing dates to keep the transition smooth.
Bottom Line
There’s no one-size-fits-all answer to buying and selling at once. But for a lot of homeowners, leading with the sale makes moving easier on their mind and their wallet.
Let’s connect, so you can navigate selling and buying with more confidence, more financial power, and less stress.
More Homes, Better Prices: A Buyer’s Summer

If you’ve thought about buying a home in the past few years, you may have run into two frustrations: asking prices that kept climbing and too few homes to choose from.
In many places, both sticking points are letting up this summer, with lower asking prices and more homes for sale. Let’s look at the trends, and what they mean for your search.
Sellers Are Pricing To Attract Buyers
According to Realtor.com, the national median asking price was $430,000 in June, nearly $11,000 under what it was the year before (see graph below):

That’s the eighth month in a row that the typical asking price has dipped below where they were the previous year, according to the same Realtor.com report.
And while falling prices can sound worrying, this isn’t a sign of an impending crash. We’re talking about asking prices, not sold prices. This is a sign that today’s sellers are meeting the market where it is and pricing to draw buyers. And that’s actually something normal we’d expect from the market. As Danielle Hale, Chief Economist at Realtor.com, puts it:
“Sellers are reading market conditions and are pricing accordingly from the start rather than listing high and cutting later, and buyers are taking note and making bids. This is a welcome sign that we are in a functioning market.”
Asking prices were never going to climb forever – now they’re just settling closer to what buyers can actually pay. That signals a healthier market, and sellers re-adjusting their expectations.
More Homes Are Available Now
If you’ve spent the past few years watching homes disappear before you could even schedule a tour, this is for you.
Supply is starting to catch up. According to Realtor.com, the number of homes listed for sale in June was the highest June number we’ve seen in three years (see graph below):

This means more options for you and less competition for each one.
Now, supply is not back to normal everywhere. As you can see, we’re still down from where we were back in 2017-2019. But in many places, it’s better than it’s been in a while. Here’s how that helps you.
You don’t have to rush an offer just to stay in the running, and you have better odds of finding and landing the right home, not just the one that’s available. Plus, you’ll have more room to negotiate, so you’re searching from a stronger position than buyers had even a year ago.
Why This Is Encouraging if You’re Buying Your First Home
For first-time buyers looking for lower-priced homes, these trends line up especially well. Mischa Fisher, Chief Economist at Zillow, explains:
“The lowest price tiers are exhibiting some softness in terms of price, they also had the most listing-activity growth, the first time since 2022 that’s been the case.”
So, if you’re searching for your first place or your next house, there’s a little more to choose from and a little more give on price.
Bottom Line
If a tight budget or a thin selection has kept you from buying a home, now might be the time to restart your search.
Ready to see what’s available here? Let’s connect.
Student Loans Are Back in the News. Don’t Let It Put Your Homeownership Plans on Hold.

Student loans are back in the spotlight. And whether you’ve been following the headlines closely or just catching bits and pieces here and there, there’s a good chance they’ve been on your mind lately.
And if you’re questioning whether you have to hit pause on your plans to buy a home, here’s the thing you have to remember:
Having student loans doesn’t automatically mean buying a home has to wait.
The Biggest Myth About Student Loans and Buying a Home
One of the most common misconceptions among first-time buyers is that they have to pay off their student loans before they can qualify for a mortgage. But in most cases, that’s just not true.
As an article from Redfin explains, student loans usually get evaluated the same way other debts do, like credit cards or car payments:
“Yes, you can get a mortgage with student loan debt. Lenders primarily assess your debt-to-income (DTI) ratio, which compares your monthly debt payments, including student loans, to your gross monthly income. Having student debt doesn’t automatically disqualify you if your DTI is within acceptable limits.”
So having that loan on your credit report isn’t some special red flag that immediately disqualifies you.
Instead, lenders look at your overall financial situation, including your income, credit history, and more. Student loans are one piece of that puzzle, but they’re not the entire picture.
You’re in Better Company Than You Think
Just to really drive this home, here’s a stat from the National Association of Realtors (NAR) that proves you can have student debt and still buy a home. Their research shows 33% of first-time homebuyers still had student loan debt.

That’s 1 out of every 3 first-time buyers. The median amount they owed? $30,400.
Let that reassure you that people are buying homes with student debt every day. And carrying student loans doesn’t automatically put homeownership out of reach.
Don’t Count Yourself Out Before You Even Try
At the end of the day, here’s where a lot of buyers trip themselves up. They assume the worst and never even check what they could actually qualify for. But your situation is more unique than a blanket “no.”
If your income is steady and the rest of your finances are in decent shape, buying a home could be more realistic than you think. The only way to know for sure is to actually run the numbers with someone who does this for a living.
You may discover you’re closer to buying than you think.
Bottom Line
Student loans don’t have to be the thing standing between you and owning a home. If you’ve been putting off your homebuying plans because of that debt, talk to a lender about your options. It may not be the barrier you think it is.
The 1 Factor That Explains Everything Happening with Home Prices Right Now
You’ve probably heard that home prices are cooling off. And that’s true – nationally. But zoom in on individual markets across the country, and the picture looks completely different depending on where you are.
Some areas are still seeing solid price growth. Others have gone flat. A few have actually dipped slightly negative. So, what’s causing all of that variation?
It All Comes Down to Inventory
Here’s the simple version:
- When there are more homes for sale, buyers have options.
- More options, means less competition.
- Less competition means sellers can’t push prices as high.
On the flip side, when inventory is tight, buyers are competing over a small pool of homes, and that pushes prices up.
That dynamic is playing out right now in a really visible way across the country.
Markets where inventory has climbed back to, or above, normal pre-pandemic levels are seeing prices flatten or fall slightly. Markets where inventory is still well below those 2019 benchmarks are still seeing prices rise. As Lance Lambert, CEO of ResiClub, puts it:
“Home prices are still climbing a little year-over-year in many regions where active inventory remains well below pre-pandemic 2019 levels, such as pockets of the Northeast and Midwest.
In contrast, some pockets in states like Texas, Florida, and Colorado — where active inventory exceeds pre-pandemic 2019 levels by a solid clip — are seeing modest home price pullbacks or flat pricing.”
The Maps Say It All
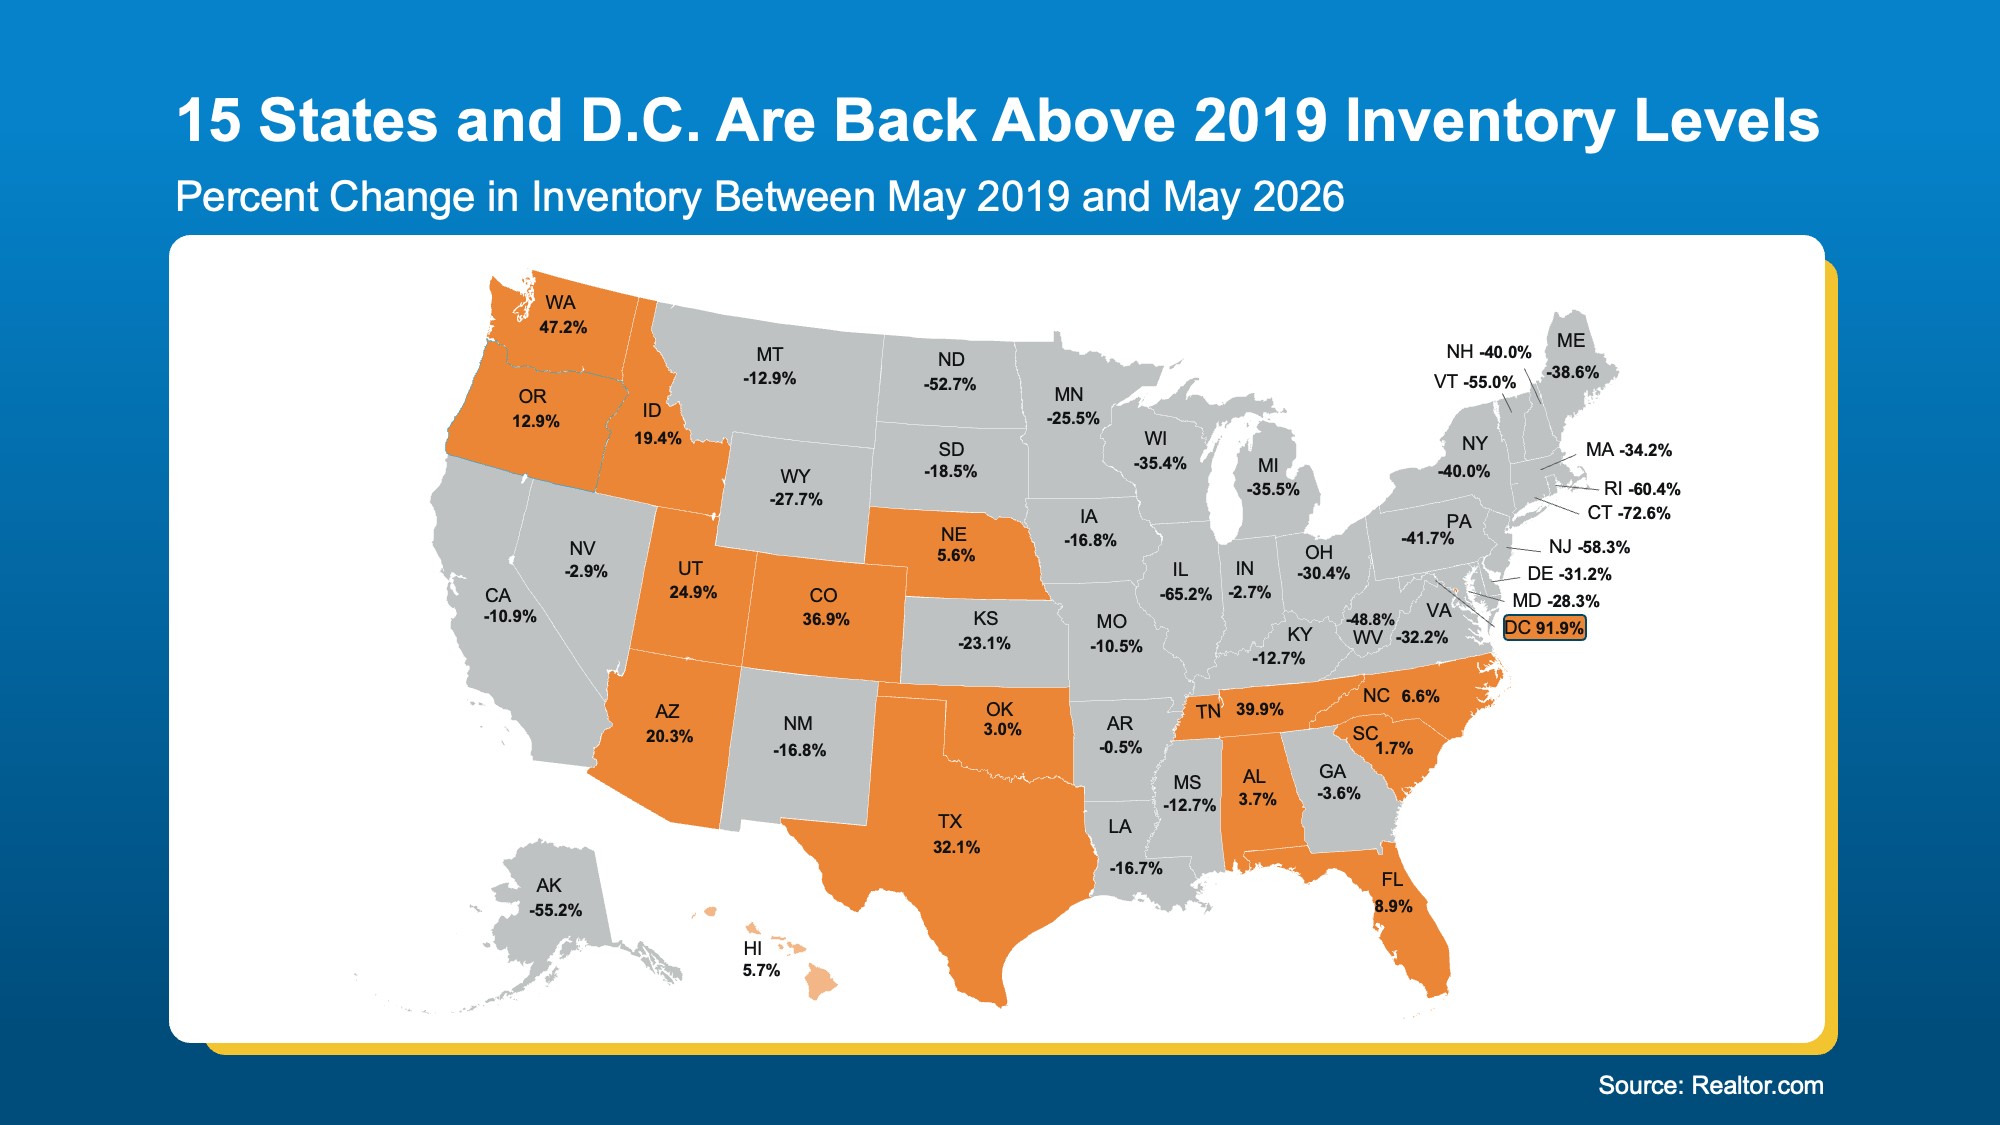
Take a look at where inventory stands today compared to 2019. In most places (the states in gray below), inventory still falls short of where we were back then. And that’s exactly why prices are climbing, albeit moderately, in the vast majority of states.
But you’re probably more interested in where prices are falling a bit, since that’s what is making headlines. So, let’s prove out how much inventory affects prices in those spots.
According to Realtor.com, 15 states and Washington, D.C. are now back above pre-pandemic inventory levels, and some by a wide margin (see the orange in the map below):
Now, let’s look at the latest Federal Housing Finance Agency (FHFA) data to see what’s happened to home prices in those same states over the past year (again, you’ll want to focus on the orange in the next map).
See how those line up pretty closely with the areas seeing more homes for sale today?
The overlap isn’t a coincidence. It’s cause and effect.
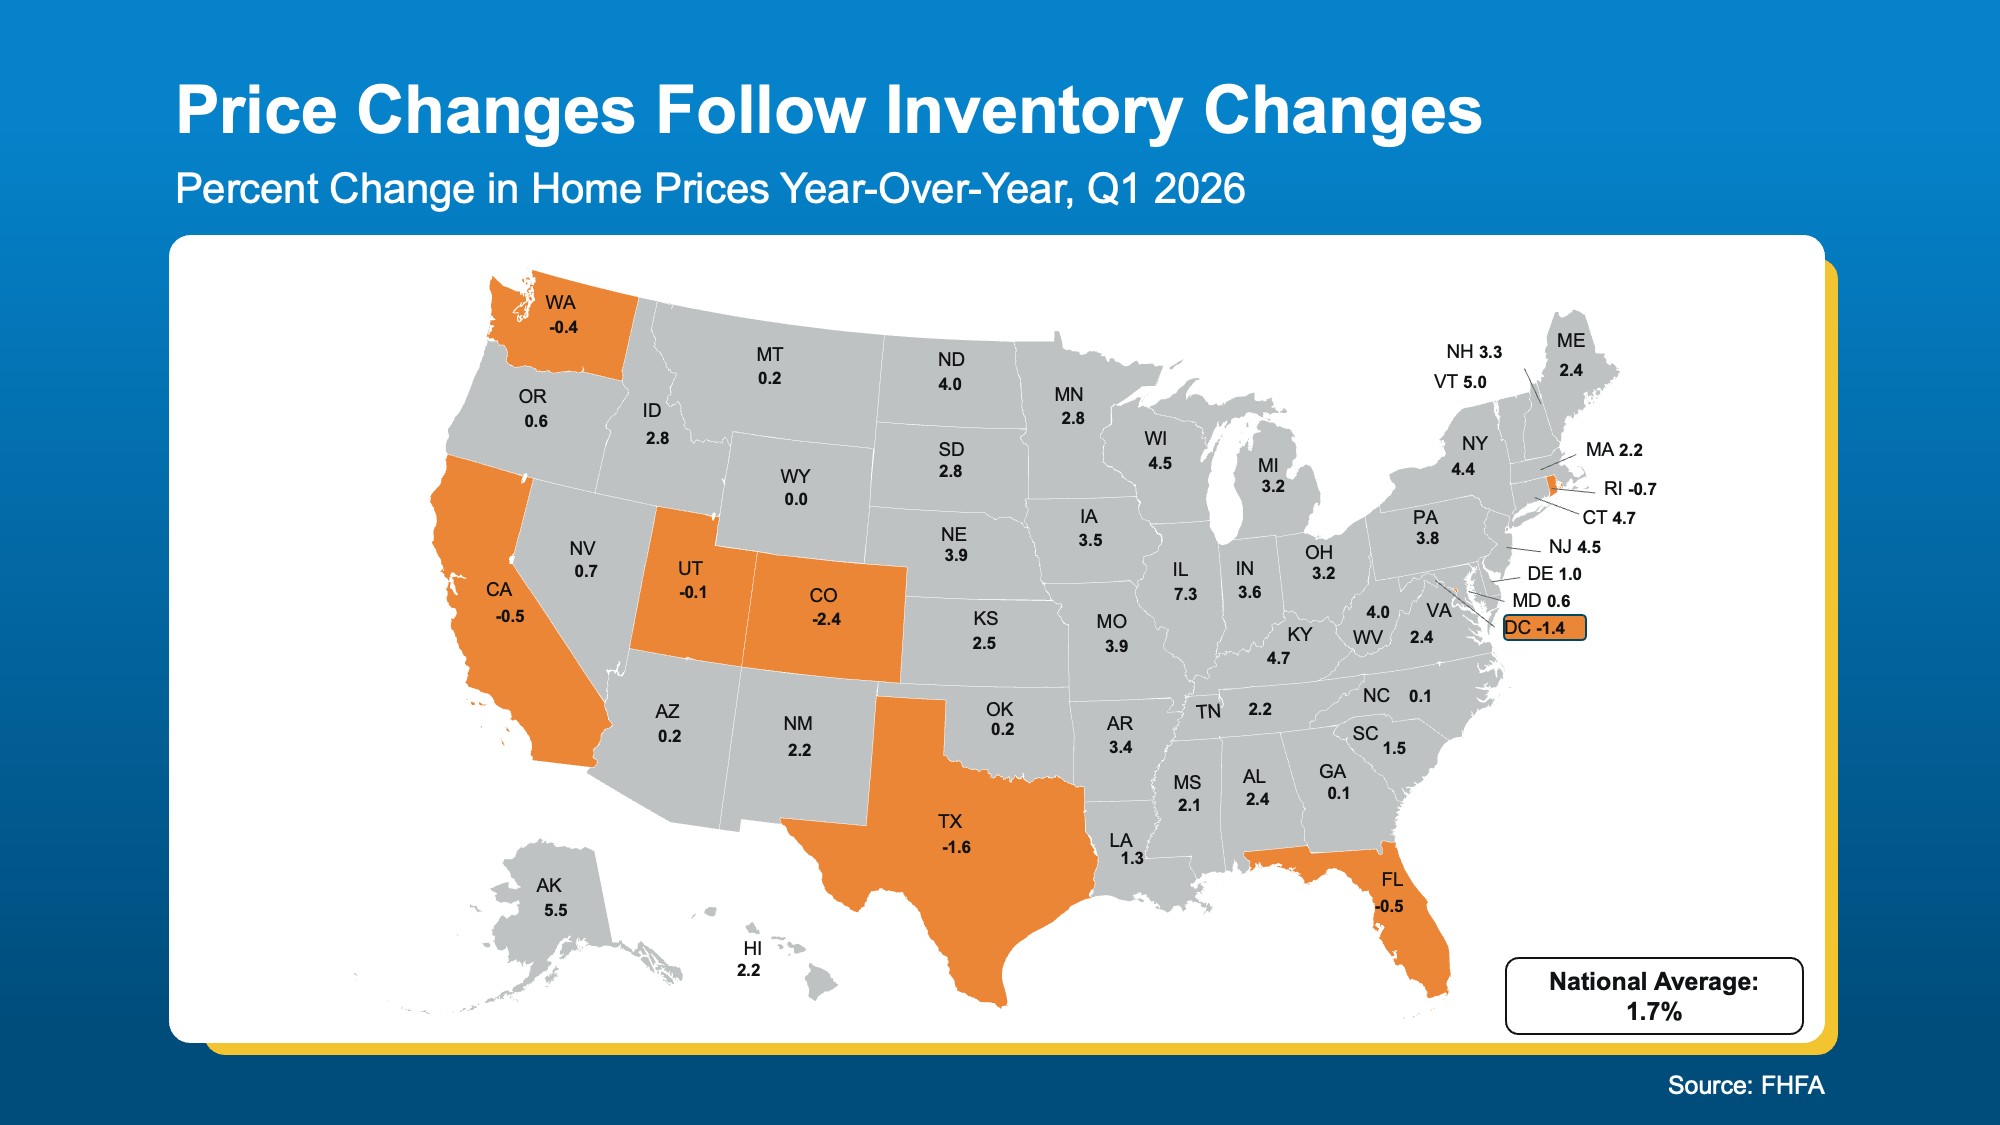
The national average of 1.7% price growth is accurate, but it’s an average of two very different stories happening at the same time – the few areas experiencing mild declines and the overwhelming majority that are still seeing prices rise.
What This Means If You’re Buying or Selling
If you’re a buyer, the market you’re shopping in matters a lot right now. In places like Texas, Colorado, or Florida, you may have real negotiating power – more choices, less competition, and sellers who are more motivated to make a deal. In tighter markets like much of the Northeast, you’re still likely facing a lot of competition.
If you’re a seller, pricing strategy is everything. In markets where inventory has risen, overpricing is one of the fastest ways to linger on the market and eventually sell for less than you would have with the right price from day one. In markets where inventory is still low, you’re in a strong spot, but getting your price right still matters if you want to attract serious buyers quickly. Either way, that’s where a local real estate agent earns their keep.
Bottom Line
When it comes to prices, where you are matters more than ever right now, and a local real estate agent is the best person to help you make sense of it.
Reach out today and let’s build a plan that fits our market.
The Real Reason Some People Are Still Moving Right Now
You may be telling yourself you’re going to wait to move – maybe you’re hoping mortgage rates will come down, prices will fall, or the market will feel a little easier.
And honestly? A lot of people feel that way right now. But here’s what some are starting to realize.
Waiting doesn’t usually fix the thing that made you want to move in the first place.
Your family still desperately needs more room. Your empty nest still feels too…empty.
Your parents or grandparents still need you to live closer.
You just got married… or divorced.
Your vision of retirement has you living somewhere else.
Eventually, life can reach a point where waiting feels harder than moving.
That’s why some people are still deciding to buy right now, even in today’s market. Not because conditions are perfect. But because the life changes behind their move never really went away.
And maybe that’s exactly where you are too. If so, you’re certainly not alone.
The Real Reasons People Move
Data from the National Association of Realtors (NAR) shows 1 in 5 buyers last year said they felt like they had to purchase a home at that time, no matter the market.
That’s an important reminder right now. Sure, the dollars and cents of your move have to make sense for you. But big life changes happen whether mortgage rates and home prices are high, low, or somewhere in between.
And those big life events happen more than you may think. NAR says roughly 22.5 million people experience major life changes in a typical two-year span (see graph below):
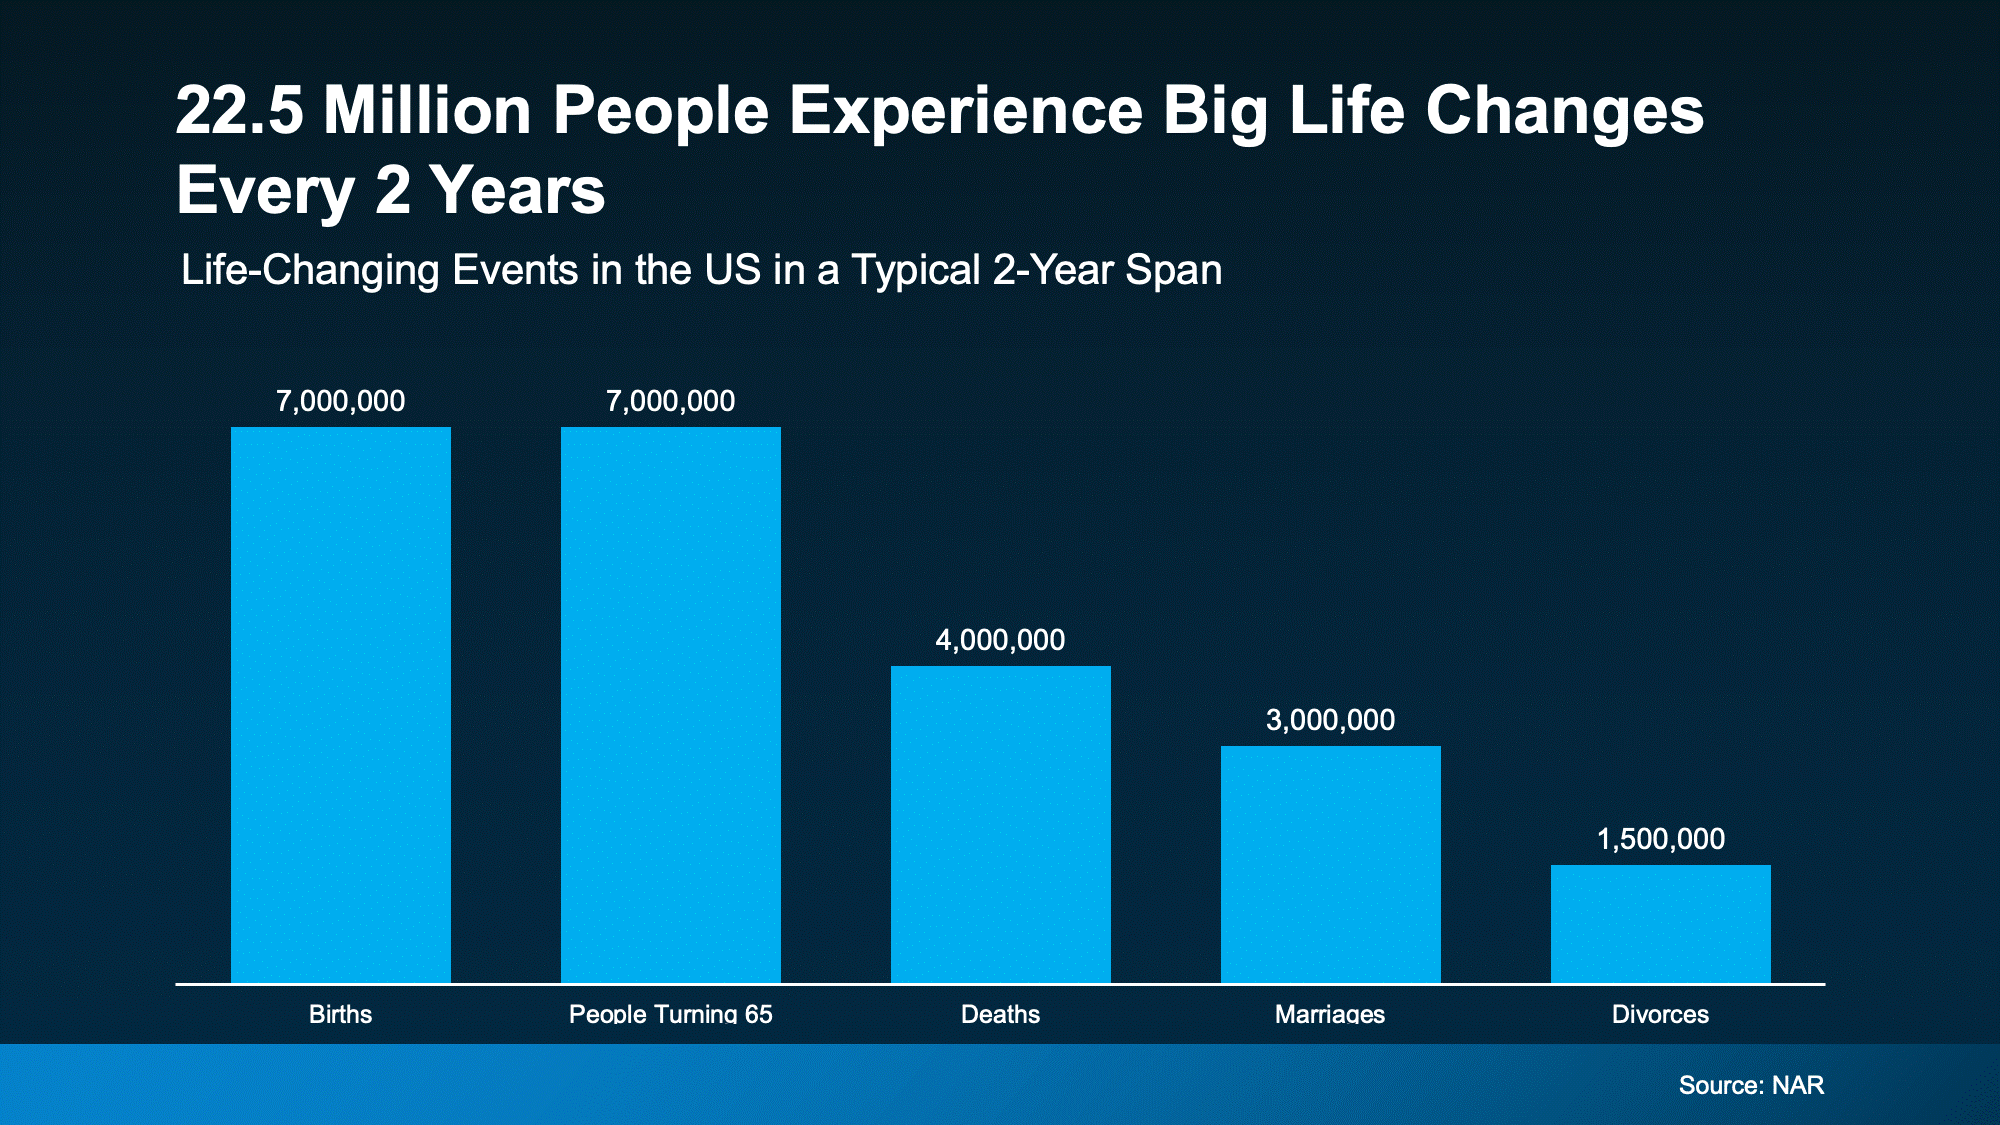
These are exactly the kinds of things that can change how much space you need, where you want to live, or what kind of lifestyle makes sense now. Chen Zhao, Head of Economics Research at Redfin, explains:
“Life doesn’t stand still—people get new jobs, grow their families, downsize after retirement, or simply want to live in a different neighborhood.”
And that’s what makes waiting so hard. Every month you spend hoping the market changes is another month living in a house that no longer works for your life. It’s stressful to feel stuck. And that feeling usually doesn’t disappear.
There May Be More Opportunity Than You Think
But while affordability is still a challenge, there may still be a way for you to make your move.
The number of homes for sale has been growing for 4 straight years (see graph below). That means more homes to choose from and, in some markets, more room to negotiate than buyers had just a few years ago.
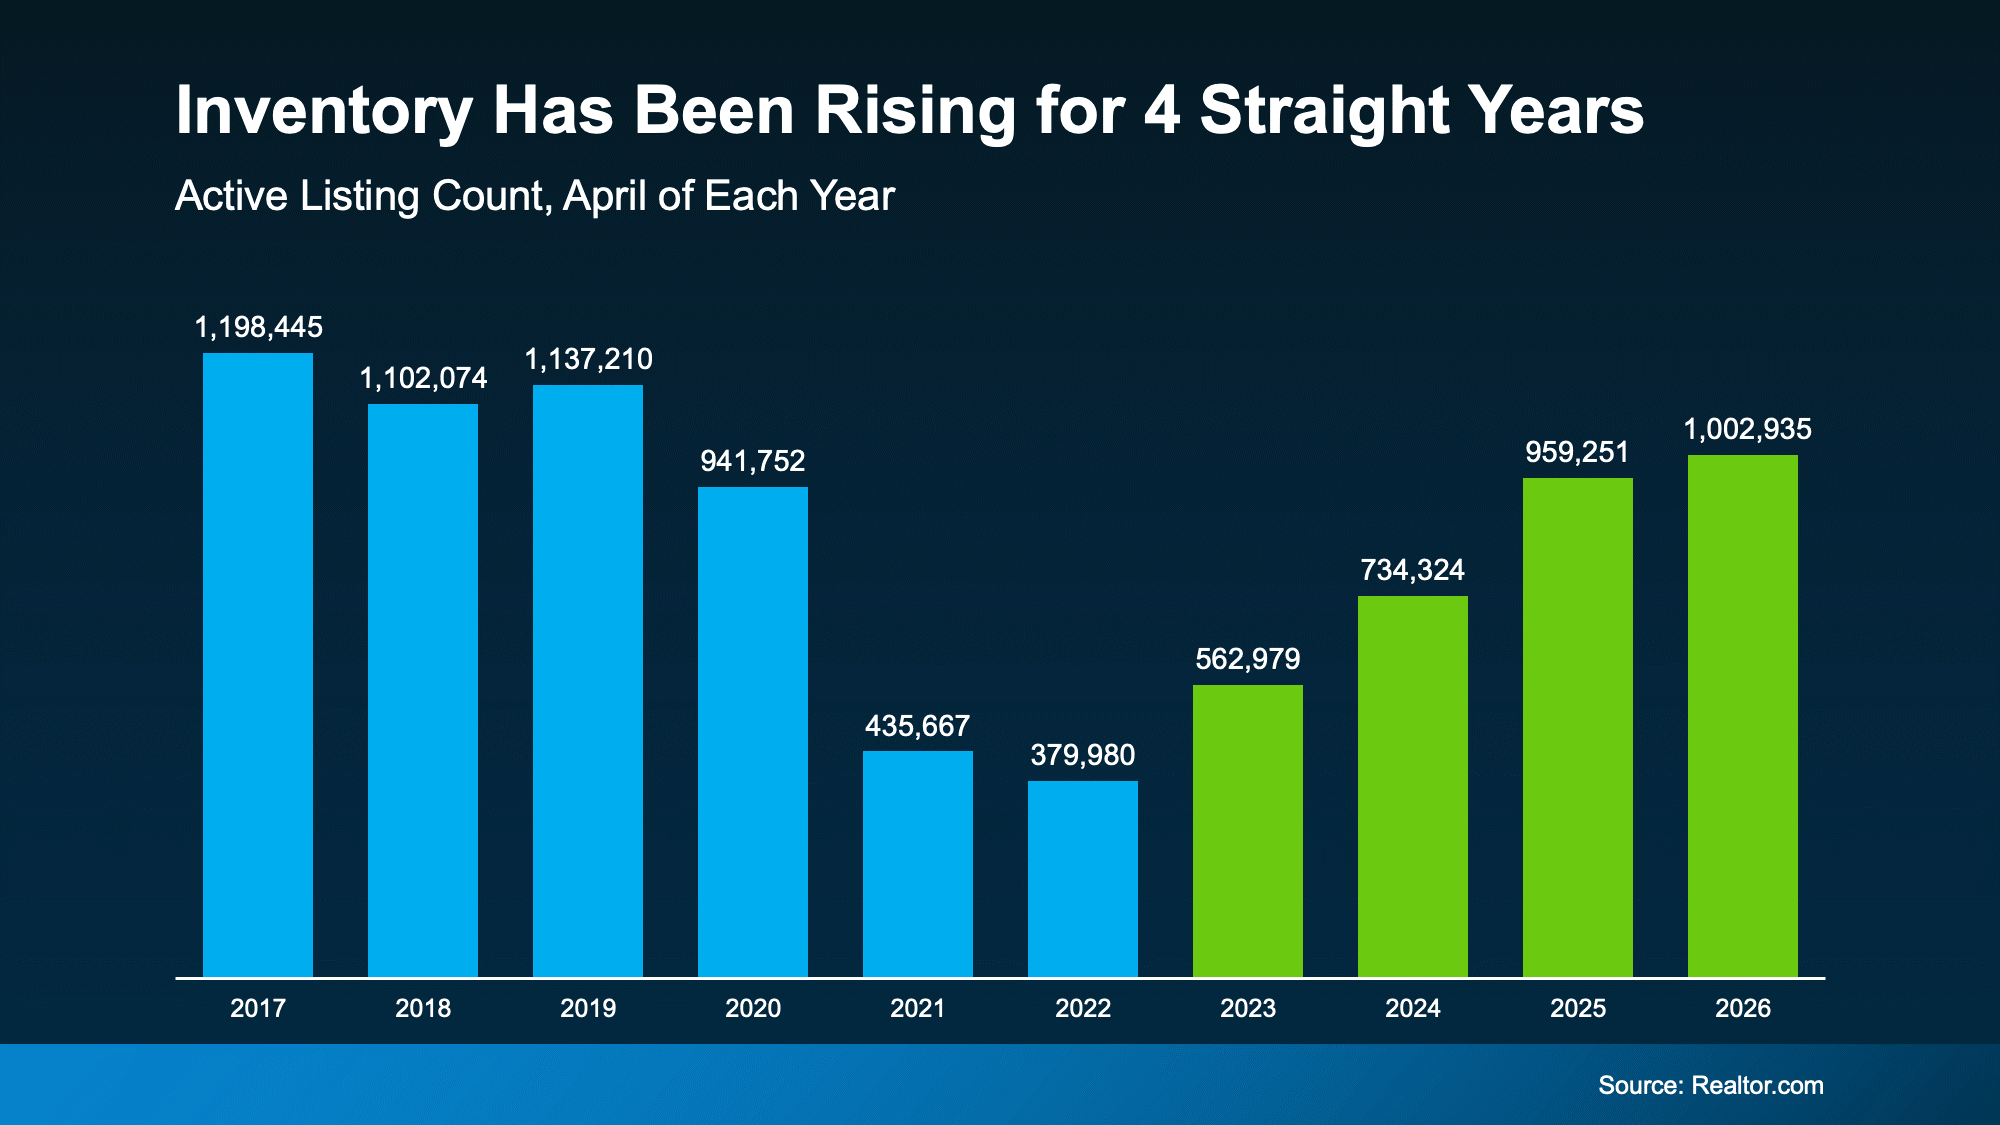
That doesn’t mean moving is suddenly easy. But it does mean some buyers are finding ways to make a move work. So, if you’ve been putting your plans on hold, maybe the question isn’t just:
“What’s the market doing?” or “When will it get better?”
Maybe ask yourself this, too: “Can I still live where I’m at right now and make it work?”
If the answer to that second question is “no,” it may be worth having a conversation about what your options look like today – despite where rates or prices are. You could find your move is still possible after all. With more homes for sale, there’s a better chance to find one that fits your life (and your budget) right now.
Bottom Line
Life changes. Priorities shift. Families grow. Kids move out. Careers evolve. And eventually, the house you’re in may stop fitting the life you’re living.
If that’s been weighing on you lately, let’s talk through what your options could realistically look like today, no matter where rates or prices are.
Life can’t always wait for perfect market conditions. Maybe you don’t have to either.
Wondering If You Should Still Buy a Home Right Now? Here’s What To Keep in Mind.
With economic headlines, global events, and near constant talk about affordability, you may be wondering if this is the right time to move. But here’s what you need to remember.
While recent events do have some impact on the housing market, they don’t take buying off the table. You just have to use a different strategy.
Mortgage Rates Have Been Up Slightly – Here’s Why
After trending down for most of 2025, mortgage rates have been higher again for over roughly a month now. And experts say it’s a result of what’s happening overseas and in the broader economy. As Mark Fleming, Chief Economist at First American, explains:
“Mortgage rates have recently moved higher, driven by geopolitical uncertainty and rising energy costs that are contributing to inflation concerns.”
But what does that really mean for you? Should you wait for everything to settle back down before you buy a home?
The short answer is no. You don’t have to wait.
Your Window To Buy Didn’t Close
It’s true that a month or so ago, when rates were just shy of 6%, buying felt a bit more affordable. And now that rates are hovering around the mid-6s, monthly payment costs are higher.
But zoom out for a second.
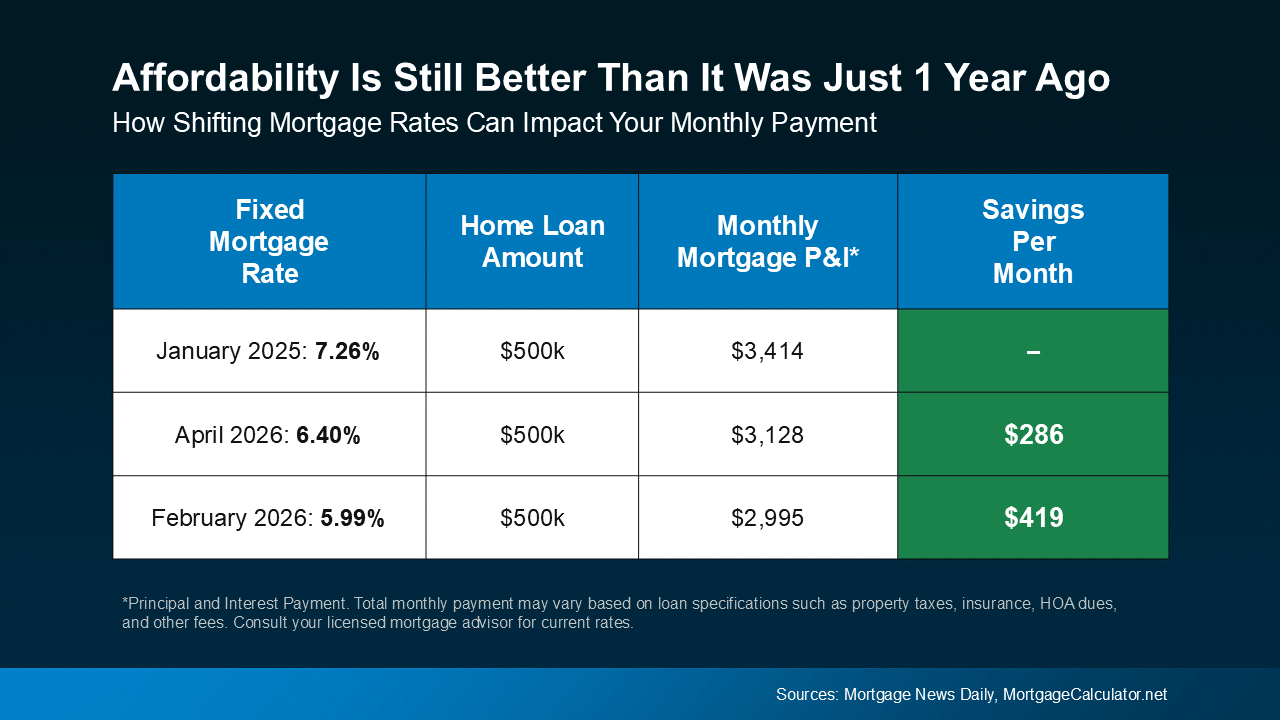
Let’s say you’re taking out a loan for $500k. Even with rates in the mid 6s, you’re still saving roughly $300 on your monthly payment compared to buyers who made their purchase early last year.
That means this recent increase in rates hasn’t erased the progress we’ve seen. Buying is still more affordable than it was just one year ago (see below):
Sure, your monthly payment would’ve been a little less expensive a few weeks back. But hindsight is always 20/20.
The goal moving forward shouldn’t be to perfectly time the market. Things change too quickly for that. Instead, the real goal is to make the best decision you can based on where things are today. And the best advice anyone can give is: brace for volatility.
When It Comes To Rates, Expect the Unexpected
Mortgage rates are going to continue to be move around in the weeks or months ahead as new information and economic reports come out.
Try to remember, you can’t control global events or where rates go next week (or even next month). But you can control how you prepare. If you do that, it becomes less about the headlines, and more about your situation.
If You Want or Need To Move, You Still Can
The simple truth is, if you want or need to move, you still can.
Some buyers are choosing to move forward right now because their needs haven’t changed. A growing family, a job relocation, a lifestyle shift – those things still matter.
And for buyers who do decide to move forward, there are ways to make it work.
For example, you could explore options like adjustable-rate mortgages (ARMs) to get a lower rate upfront. That may or may not be the right fit for you, but it highlights an important point: there are strategies that can help you move, even now.
What matters most is having a plan.
And working with the right agent and lender is a big part of that. With expert help, you’ll:
- Understand your budget and what the math looks like at today’s rates.
- Explore your financing options, including ARMs and assistance programs.
- Have trusted guidance from experts who’ll keep you up to date throughout the process.
Bottom Line
Even though there’s some uncertainty, that doesn’t mean you’re out of options.
If you need to move, you still can. Let’s connect so we can explore all your options and make your move happen.
Before You Fall in Love with a House, Do This First.
Be honest. Have you started looking at homes online yet? If you have, it’s already time to get pre-approved. Because here’s what not enough people know.
If buying a home is on your radar – even if it’s more of a someday plan than a right now plan – you don’t want to wait until later on in the process to tackle this step.
No matter what you’ve heard, pre-approval isn’t about commitment. It’s about clarity. And here are the two big ways pre-approval sets you up for success.
You Know Your Numbers Up Front
During the pre-approval process, a lender will walk through your finances and tell you what you can borrow based on your income, debts, credit score, and more. And once you have that number, your search becomes a lot more focused.
With a mortgage pre-approval, you know what you can borrow, so it’s easier to figure out your ideal price point, and what you can actually afford. And that clarity is key. Because if you just start browsing online and just guess at your price point, you run the risk of falling for a house that’s outside of your price range – or missing out on ones that aren’t.
You want this number to be clearly defined before your search. Here’s why.
You Can Move Quickly When You Find the One
This is how a lot of home searches go today. You scroll through listings just to see what’s out there, and then it happens. You fall in love with something you’ve seen online.
If you’re already pre-approved? You’re probably in great shape.
But if you’re not…
Instead of being able to jump on that house and quickly make an offer, you have to scramble to get a lender, gather the financial documents, and then submit the necessary pre-approval paperwork first. And while you’re waiting to hear back from your lender, someone else who’s more prepared could beat you to the house. As Bankrate explains:
“The best time to get a mortgage preapproval is before you start looking for a home. If you find a home you love but don’t have a preapproval in hand, you likely won’t have time to get preapproved before you need to make an offer . . .”
And that’s avoidable, with the right prep.
Because while you can’t control when the right home shows up, you can be ready for it. Think of it like showing up to the starting line with your shoes tied and your warm-up done – while everyone else is still looking for parking.
It’s not about rushing your timeline. It’s about removing the delay between finding the right home and being able to move on it.
One Thing You Need To Know About Pre-Approvals
Speaking of timing, pre-approvals do have an expiration date. So, be sure to ask your lender how long it’s good for. The Mortgage Reports explains:
“Mortgage preapproval letters are typically valid for anywhere from 30 to 90 days. However, a preapproval can be updated and extended if the lender re-checks your information.”
Doing the right prep and knowing this information can make the whole process a lot smoother.
You don’t have to be ready to buy to be ready to buy.
Getting pre-approved doesn’t mean you’re committing to buy right now. It just means you’ve taken a step to understand your numbers. And when a home catches your attention, you’re prepped and good to go.
Bottom Line
Ask yourself this: if your perfect home popped up tomorrow, would you be ready to make a move?
If the answer is no and you want to buy, it may be time to get pre-approved. You don’t feel behind before your search even officially kicks off.
The #1 Reason Buyers Walk Away (And How To Get Ahead of It)
You may have seen headlines on social saying the number of buyers backing out of their contracts is on the rise – and has recently reached a high not seen since 2017. That can sound intimidating. But it varies a lot by market.
And here’s the key thing to understand if you want to sell. A lot of the time, there’s one common cause. And it’s something you can actually control.
Here’s what you can do to get ahead of the biggest dealbreaker before it ever becomes a problem.
The Top Dealbreaker: Issues That Pop Up During the Inspection
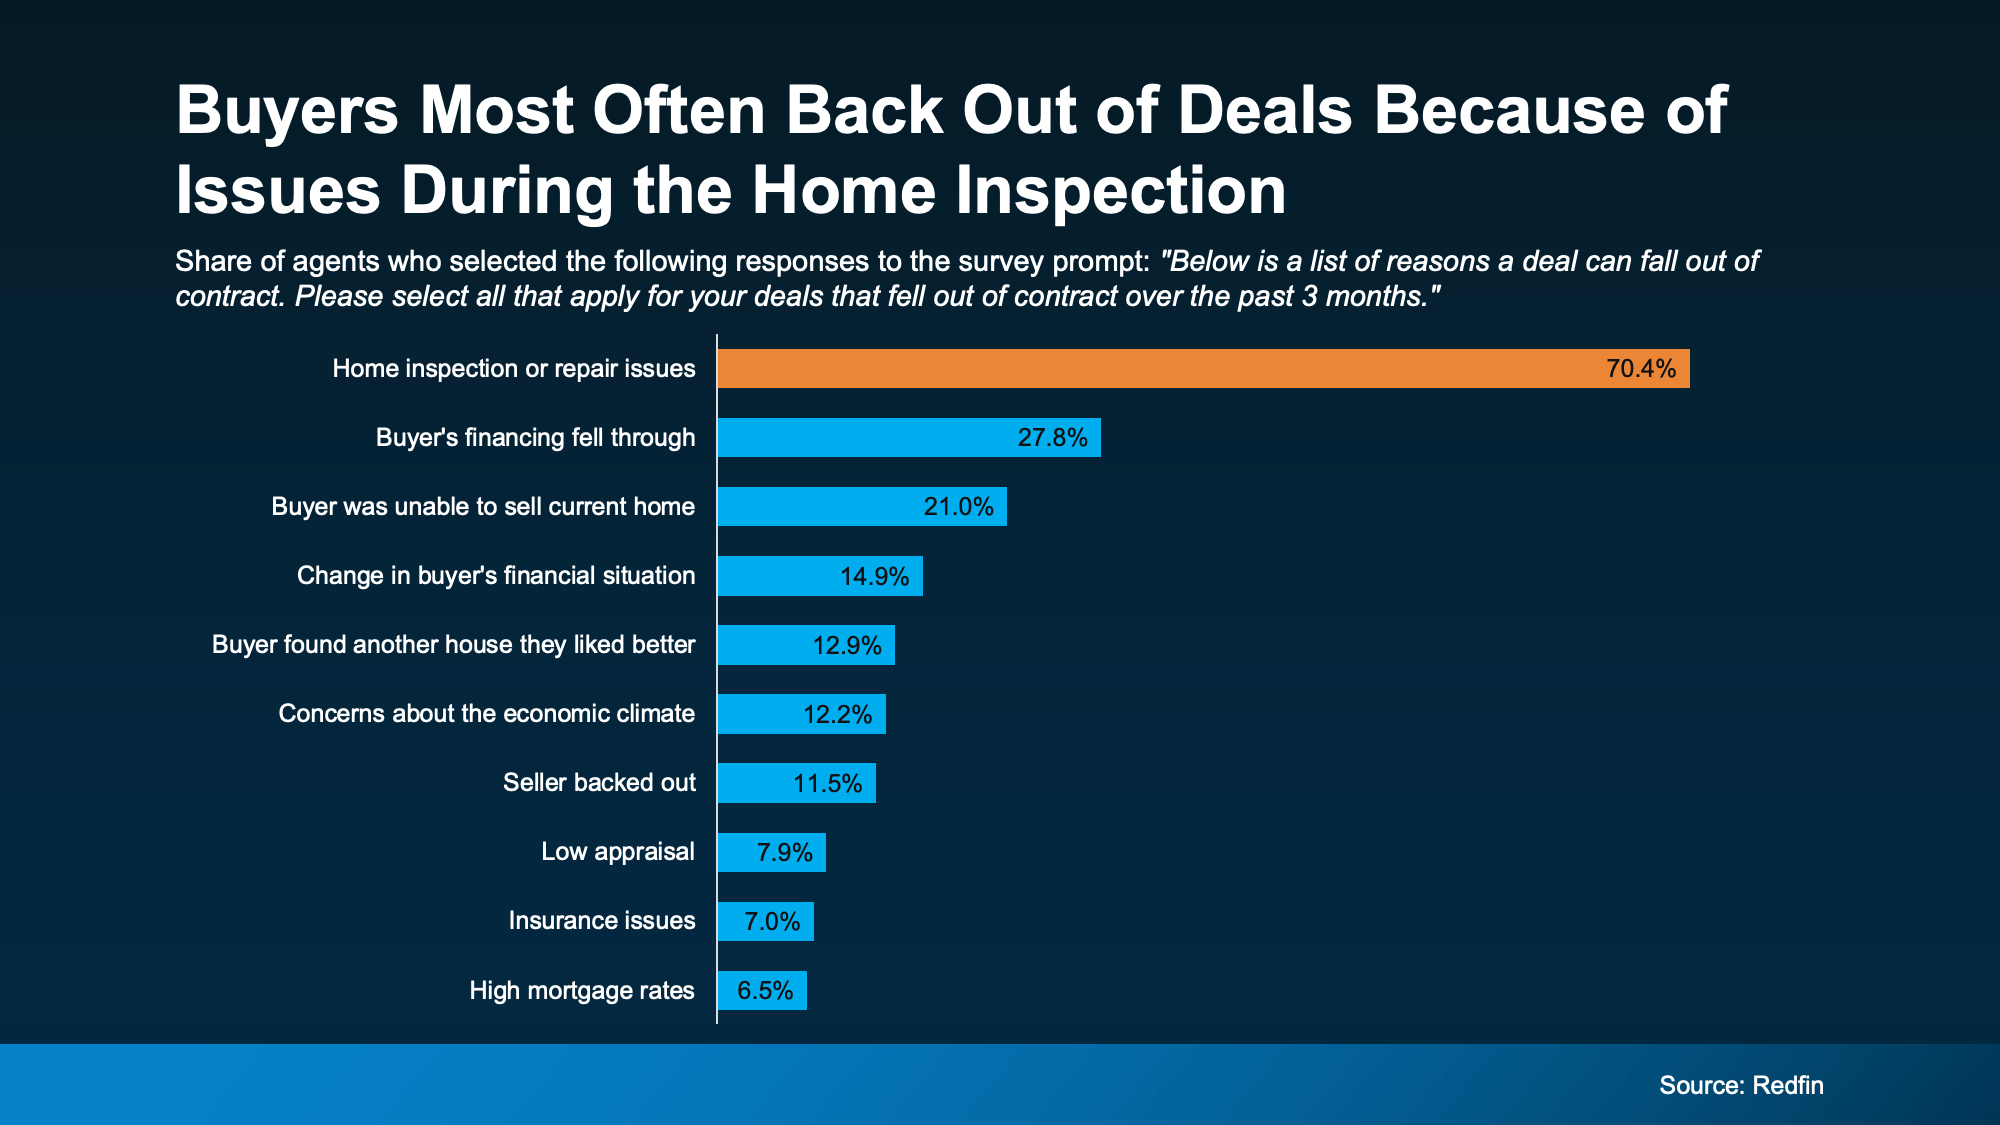
A Redfin survey shows over 70% of recently cancelled contracts happened because of issues during the home inspection (see graph below):
And that makes sense. Because today’s buyers have something they didn’t have a couple of years ago: options.
Why Fixing Things Before You List Matters More Today
A few years back, when buyers felt rushed or boxed in due to the limited number of homes for sale, they were more willing to overlook issues.
But in today’s market, skipping essential repairs is one of the fastest ways to lose a deal.
Now that there are more homes to choose from, buyers can be more selective. If a house feels risky, outdated, or like it’s hiding expensive surprises, they’re a lot more likely to walk away. So, what do you have to fix? Just ask an agent.
How Your Agent Can Help Give You the Edge
A local agent will be able to walk through your house and offer advice on what to tackle based on your specific home, your market, and what buyers are prioritizing in your area. They’ll also have first-hand knowledge about some of the biggest turnoffs for buyers today. And you can use that expertise to prevent future headaches.
For example, according to Zillow, these are some of the issues buyers will care the most about:
- Roof leaks or damage: sagging, leaking, etc.
- Plumbing problems: standing water, leaks, water damage, etc.
- Electrical concerns: outdated or exposed wiring, missing GFCI outlets, etc.
- HVAC issues: non-functioning units
- Pest or insect damage: termite colonies, etc.
- Hazardous materials: lead, mold, asbestos, etc.
- Safety/code violations: missing smoke detectors, windows stuck closed, etc.
- Structural problems: cracks in the foundation, sagging floors, etc.
Odds are not all of this even applies to your house. Maybe only 1-2 things do. Or maybe none of them do. It just depends. But an agent will have the tools and resources to help you figure it out and stay one step ahead.
The Benefits of a Pre-Listing Inspection
To buyers, these aren’t cosmetic issues. They’re trust issues. And that’s what you need to watch out for today. Once buyers start wondering “what else might be wrong,” it’s hard to recover momentum.
That’s why some agents are even recommending a pre-listing inspection as a sneak peek into what buyers will see on their own inspection. With that insight, you can:
- Fix concerns before you list, or disclose issues upfront
- Avoid having to respond or negotiate under pressure
- Stop scrambling to find contractors with availability before your closing date
But remember, you don’t have to fix everything. You just have to be strategic about what you do tackle, so you and your buyer aren’t caught off guard.
And that’s why you need an agent who can:
- Decide if a pre-listing inspection is worth it where you live
- Recommend a trusted inspector (if you decide to get one)
- Look at the results with you to identify true dealbreakers in your market
- Help you decide what to fix or what to credit
- Make sure you avoid over-spending or under-preparing
Bottom Line
One of the biggest dealbreakers for buyers today is inspection issues – and that’s something you can control. You just need to be proactive about high-impact repairs before you list.
If you want help figuring out where to focus, let’s connect so we can keep your sale on track from day one.
