

 Facebook
 X
 Pinterest
 Copy Link
Thinking About Tapping into Your 401(k) To Buy a Home? Read This First.
Lately, headlines have floated an eye-catching idea about tapping into your 401(k) to cover a down payment on a home. Maybe you’ve caught the buzz and wondered whether that money could get you into a home faster, especially with affordability as tough as it is.
Here’s what you need to remember. Pulling from your retirement savings is a big decision, so take time to weigh all your options first and be sure to talk with a financial expert before you do anything.
Why Dipping into a 401(k) Can Be Tempting
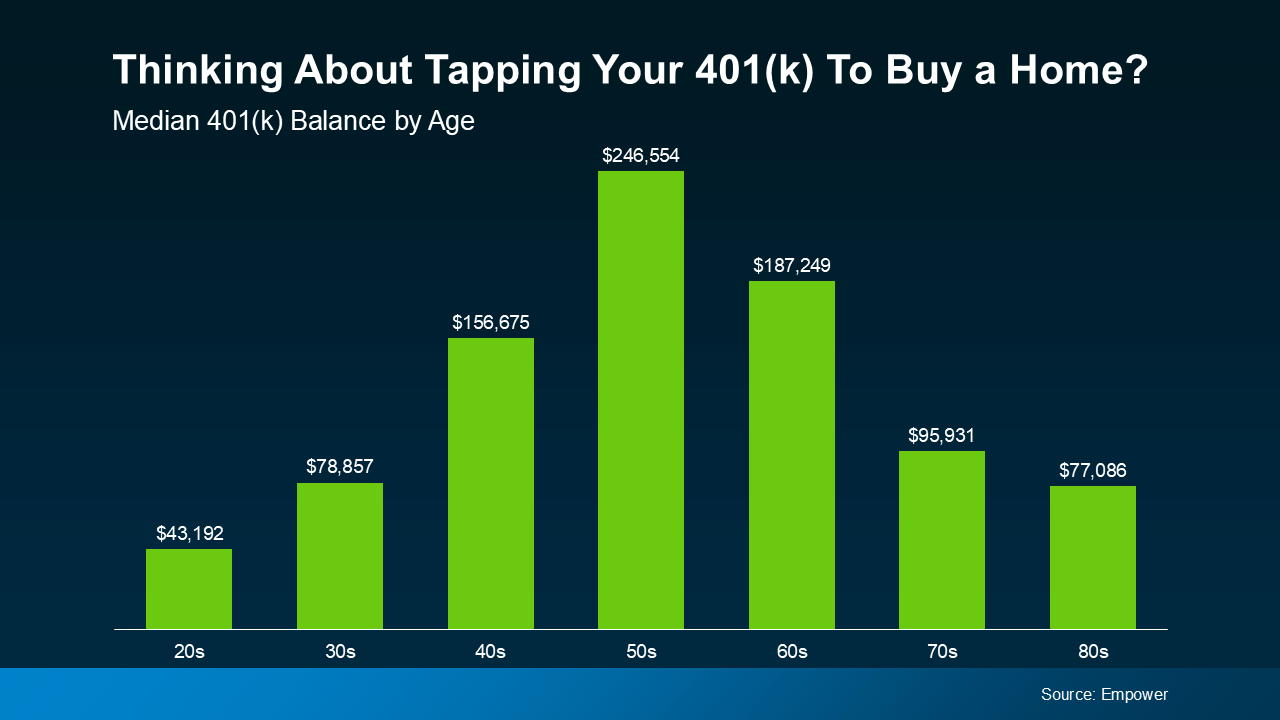
Data from Empower shows many Americans have built up considerable retirement savings. The median 401(k) amount for anyone in their 40s-60s is six figures (see graph below):
 And when you’ve got a good chunk saved and your dream home is right there, reaching for it can feel like an easy call.
But dipping into your retirement savings to buy a home could cost you a penalty and set back your finances later on. That’s why it’s a good idea to explore other options for your down payment first. As Redfin says:
“If you’re struggling to save enough for a down payment, you may be wondering if tapping into your 401(k) is the right option. While it’s possible, doing so comes with significant risks, like early withdrawal penalties and lost investment growth.”
Before you decide, have a financial advisor help you compare the upsides to the risks. Bankrate points to a few of each (see visual): 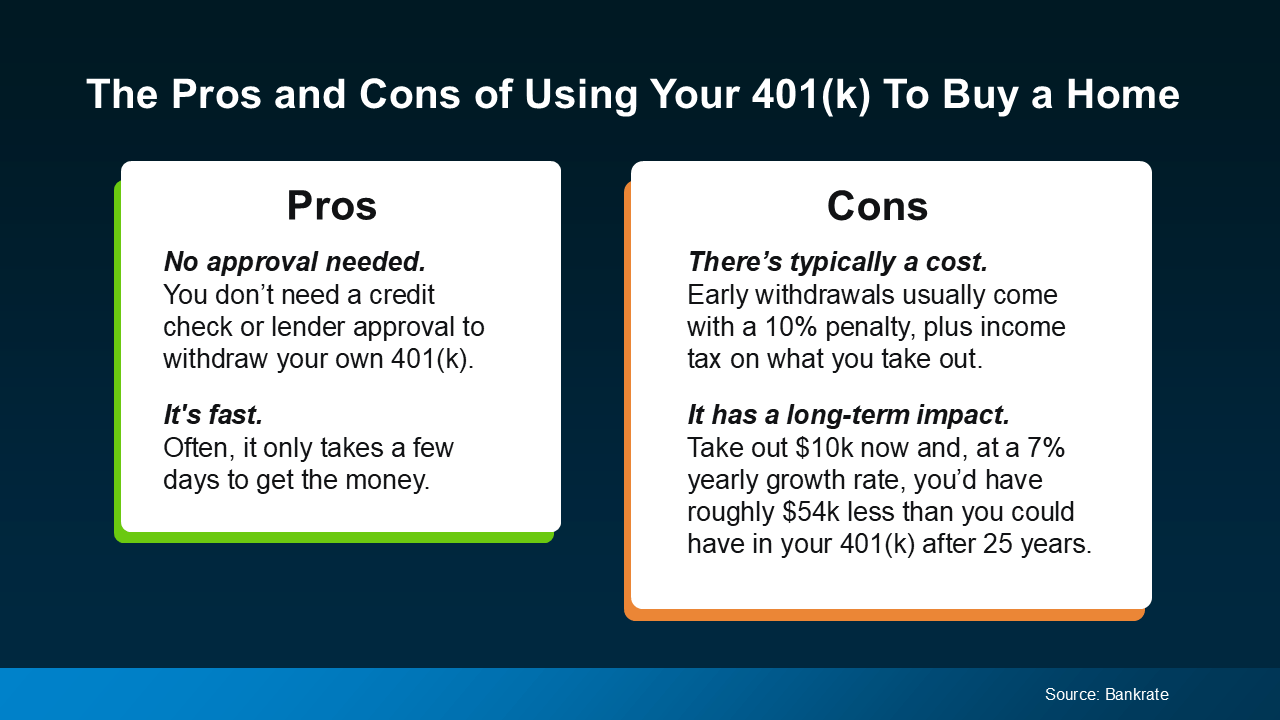 Other Options Worth Exploring First
Your 401(k) isn’t the only way to finance a home purchase. Redfin outlines a few other options to look into before you decide what to do:
- Low and No-Down Payment Loans: FHA loans, for example, allow qualified buyers to put down as little as 3.5% of the home’s price, depending on their credit scores.
- Down Payment Assistance Programs: Many national and local programs can help reduce what you pay toward your down payment or closing costs.
Make a Plan Before You Make a Move
No matter which route you take, talk with a financial expert first. The buyers who come out ahead build a solid plan with the right professionals before starting their journey to homeownership. As NerdWallet puts it:
“Even if you’re convinced a 401(k) loan is the way to go, it’s important to understand the risks at the outset.”
Bottom Line
Affordability is definitely a challenge, but that doesn’t mean tapping your 401(k) is your only way in if you want to buy.
If you’re considering using your 401(k) savings for a down payment, weigh all your options and talk with a trusted financial advisor before you make any decisions. They’ll help you make a plan to fit your goals and your budget.
August 2026 Eastside Market Update
Four months of inventory. Let that sink in. We are teetering on the edge of a buyers’ market — territory the Eastside hasn’t seen since around 2012. This is uncharted water. But uncharted doesn’t mean dangerous. It means you need a good navigator.
Let’s start with what the data is actually telling us. The median sold price came in at $1.575M — essentially flat, both month-over-month and year-over-year. After last month’s small uptick, that’s a stabilizing signal, not a collapse. Inventory is up 40%, pendings are down 8%, so buyers are buying. The market isn’t frozen. It’s just different.
Rates are sitting at 6.69%, and I keep hearing people clutch their pearls over it. Rates aren’t going anywhere meaningful anytime soon. The latest prediction I saw had rates dropping to 6.2% eventually — and that’s simply not worth putting your life on hold for. If you’re sitting on a sub-5% rate, yes, today’s rates sting. I get it. But focus on the payment, keep the home, and you’ll be fine.
Here’s the number that tells the real story: only 27% of homes sold at or above asking price, and that is likely after a 5% price drop to cancel and relist. That means three out of four are closing below list — sometimes well below. When that’s the reality, the strategy has to shift.
For sellers: the comps conversation has changed. Closed sales tell you where the market was. Active listings tell you what buyers are choosing between today. Pending sales tell you what buyers are actually willing to buy. When I sit down to recommend a list price, I’m spending more time on actives and pendings than I am on solds. Your competition isn’t a sale from four months ago — it’s the home two streets over that just listed yesterday.
For buyers: this is genuinely one of the best environments in over a decade to be a buyer on the Eastside. More choices, motivated sellers, and real room to negotiate. That said, don’t mistake a buyers’ market for a slow market — homes that are priced right and show well are still moving. Show up ready.
Lastly, as I type this update, it appears the market might be leveling out. I think prices have settled and a little balance is coming into play, but, as always, time will tell.
Here’s Why Mortgage Rates Are What They Are Right Now

If you’re waiting for mortgage rates to fall a lot before you buy, you may be waiting a while. But before you get discouraged, there’s a number working behind the scenes that’s actually good for you right now. It’s called the spread, and once you understand it, you may see today’s rates in a whole new light.
The Pattern That’s Held for 50+ Years
For starters, mortgage rates don’t move on their own. They tend to follow the 10-year treasury yield, a number tied to how investors feel about the economy.
It’s not an exact science, since plenty of other factors can move it day to day, but broadly speaking, when the economy looks strong, that yield tends to climb over time. When the outlook gets shaky, it tends to ease. For over 50 years, the 10-year treasury yield and mortgage rates have moved almost in lockstep (see graph below):

The gap between them is called the “spread.” On average, that gap runs about 1.76 percentage points. And that spread impacts your mortgage rate. A wider spread tends to push mortgage rates higher than the treasury yield alone would suggest, while a narrower spread keeps rates closer to the treasury yield.
One of the Big Reasons Rates Likely Won’t Drop Dramatically Anytime Soon
If you’re hoping mortgage rates will drop a lot, here’s the reality – they probably won’t, at least not anytime soon. One of the big reasons why comes down to that spread between the 10-year treasury yield and mortgage rates.
A few years ago, that gap got a lot wider as uncertainty in the economy pushed it as high as 3.19 points in 2023.
Now here’s the part worth noting – that gap has been narrowing lately. It’s down to about 2.01, just above the long-term average of 1.76 (see graph below):

When the gap is wide, there’s more room for rates to fall. But when it’s relatively normal, like it is now, there’s less wiggle room for rates to fall.
Why Mortgage Rates Aren’t Higher Right Now
Today’s mortgage rate is basically the treasury yield plus the spread. So, when either one moves, your rate moves with it. Here are 3 different rates, all built off today’s 10-year treasury yield of 4.68% to show you just how much the spread matters for your bottom line (see graph below):

If the spread were still stretched out like it was in 2023, rates would be pushing close to 8% right now. That’s because the spread was over a full point wider than it is today.
But now, thanks to the spread narrowing recently, today’s rate sits around 6.69%. That’s the middle scenario in that visual. That’s a big difference in your monthly payment compared what we could see if the spread was as big as it was 2023. As Logan Mohtashami, Lead Analyst at HousingWire, put it:
“Of course, mortgage spreads being better in 2026 is the housing hero story of the year . . .”
Now compare that middle bar to the 3rd one. If the spread were sitting at its exact long-term average, rates would be around 6.5%. That’s only about a quarter of a point away from where rates actually are today. That means most of the improvement in mortgage rates we should realistically expect from a shrinking spread has already happened.
In other words, the same narrowing spread that’s the reason rates aren’t close to 8% today is also a big reason why they’re not likely to fall a lot further.
Bottom Line
That’s the trade-off with a narrowing spread. Rates may not be where you want them, but they’re better than they could’ve been. If you want help figuring out what that means for your monthly payment, reach out to a local lender.
Here’s Where To Start if You’re Selling and Buying at the Same Time

If you’re a homeowner getting ready to move, one question usually comes first: should you buy your next home before you sell, or sell your current house before you start looking?
There’s no single right answer. The best call depends on your finances, your local market, and your timeline. And a trusted agent can help you weigh all of it.
But in a lot of cases these days, selling first puts you in the stronger spot.
The Advantages of Selling First
Selling is usually the trickier half of a move today, so getting it done first clears your biggest hurdle. And that’s especially true right now, because there are more homes for sale than there are buyers, which means houses are taking longer to sell than they did a year or two ago.
So how does leading with your sale pay off? Let’s start with the money.
- You Won’t Get Stuck Paying Two Mortgages
Buy before you sell, and you could end up carrying two mortgages at once. And especially since houses are staying on the market longer these days, that overlap may drag on for more time than you’d planned. And if unexpected repairs come up, it could get even more expensive.
Selling first takes that risk off the table, so you’re not multitasking homeownership. As Ramsey Solutions puts it:
“It’s best to sell your old home before buying a new one to avoid unnecessary risks and possible headaches.”
- You Can Use Your Equity To Fuel Your Move
This is always true, but one of the biggest perks of selling first is that you’ll know exactly how much money you’re walking away with. And one of the big figures that matters in that conversation is how much equity you have in your current place.
Equity is basically your house’s value minus what you still owe on your mortgage. And it adds up fast. According to Realtor.com, homeowners who’ve been in their home for 5 years have about $180,000 in equity on average. And those who’ve had their home for 6-10 years? They have over $340,000.
After you sell, you can use that money to cover your down payment or even buy your next home in cash. And knowing that profit up front helps you plan your next move.
- Your Offer Will Be Hard To Pass Up
When your house is already sold, you don’t have to make your offer contingent on that sale. In a market where buyers are taking their time, that’s exactly what a seller wants to see.
Picture it from the seller’s side. If their house has been sitting for a while, they’ll gravitate toward the offer most likely to close without a snag.
That can also give you room to ask for a little more, like repairs, since a motivated seller would rather keep things moving than lose you and wait for another offer to come in. Your agent can help you make the most of your upper hand in that scenario.
Is There a Catch?
Selling first has its tradeoffs too, and it helps to see the pros and cons side by side before you decide. Here’s a quick breakdown based on information from Zillow (see visual below):

The cons are manageable with the right plan, so talk about them with your agent. They can help you negotiate things like a rent-back, where you stay in your house for a set time after closing, or line up flexible closing dates to keep the transition smooth.
Bottom Line
There’s no one-size-fits-all answer to buying and selling at once. But for a lot of homeowners, leading with the sale makes moving easier on their mind and their wallet.
Let’s connect, so you can navigate selling and buying with more confidence, more financial power, and less stress.
July 2026 Eastside Market Update
July 2026 Eastside Market Update
Let’s talk inventory, because it’s the defining story this month. At 3.3 months of supply, we’ve blown past anything we’ve seen in over a decade. This eclipses the rough patch of 2018 — which I remember clearly — and appears to reach back to around 2014, which honestly feels like a different era. I was there for both, and this one has its own character.
Technically, we’re still in a balanced market. But the direction of travel is unmistakable: we are approaching buyers’ market territory, and buyers know it. That’s not a crisis — a market simply is. What it does is tell us how to position and strategize. And right now, the strategy conversation is everything.
On pricing: the median sold price came in at $1.56M — up 3.3% from May, but down 3.3% year-over-year. I’ll be honest, the month-over-month bump surprises me a little given the inventory backdrop. My suspicion is mix shift — if more higher-end homes closed in June, the median rises even if the broader market is softer. The year-over-year decline is probably the more honest read, and it’s consistent with where we’ve been heading. For most sellers, the prices of the last three to five years are simply not available right now. That’s a hard truth, but an important one to name plainly.
Sellers: You need to be in it to win it — and that means coming out of the gates in the best condition possible, priced accordingly (yes, that means low). When reviewing comps, use active listings only to confirm you outshine the competition — not to justify a higher price. Those homes may never sell. The first two weeks are the market’s vote, and you want a landslide.
Buyers: Opportunity is real right now, and I’d argue July and August will be especially good months to act. More inventory, less competition, and sellers with increasing motivation. That said, stay vigilant — homes priced right and presented well are still moving fast. Be brave. The buyers who hesitate waiting for the “perfect moment” often watch the best homes go to the buyers who simply showed up ready.
As always — time will tell.
More Homes, Better Prices: A Buyer’s Summer

If you’ve thought about buying a home in the past few years, you may have run into two frustrations: asking prices that kept climbing and too few homes to choose from.
In many places, both sticking points are letting up this summer, with lower asking prices and more homes for sale. Let’s look at the trends, and what they mean for your search.
Sellers Are Pricing To Attract Buyers
According to Realtor.com, the national median asking price was $430,000 in June, nearly $11,000 under what it was the year before (see graph below):

That’s the eighth month in a row that the typical asking price has dipped below where they were the previous year, according to the same Realtor.com report.
And while falling prices can sound worrying, this isn’t a sign of an impending crash. We’re talking about asking prices, not sold prices. This is a sign that today’s sellers are meeting the market where it is and pricing to draw buyers. And that’s actually something normal we’d expect from the market. As Danielle Hale, Chief Economist at Realtor.com, puts it:
“Sellers are reading market conditions and are pricing accordingly from the start rather than listing high and cutting later, and buyers are taking note and making bids. This is a welcome sign that we are in a functioning market.”
Asking prices were never going to climb forever – now they’re just settling closer to what buyers can actually pay. That signals a healthier market, and sellers re-adjusting their expectations.
More Homes Are Available Now
If you’ve spent the past few years watching homes disappear before you could even schedule a tour, this is for you.
Supply is starting to catch up. According to Realtor.com, the number of homes listed for sale in June was the highest June number we’ve seen in three years (see graph below):

This means more options for you and less competition for each one.
Now, supply is not back to normal everywhere. As you can see, we’re still down from where we were back in 2017-2019. But in many places, it’s better than it’s been in a while. Here’s how that helps you.
You don’t have to rush an offer just to stay in the running, and you have better odds of finding and landing the right home, not just the one that’s available. Plus, you’ll have more room to negotiate, so you’re searching from a stronger position than buyers had even a year ago.
Why This Is Encouraging if You’re Buying Your First Home
For first-time buyers looking for lower-priced homes, these trends line up especially well. Mischa Fisher, Chief Economist at Zillow, explains:
“The lowest price tiers are exhibiting some softness in terms of price, they also had the most listing-activity growth, the first time since 2022 that’s been the case.”
So, if you’re searching for your first place or your next house, there’s a little more to choose from and a little more give on price.
Bottom Line
If a tight budget or a thin selection has kept you from buying a home, now might be the time to restart your search.
Ready to see what’s available here? Let’s connect.
Student Loans Are Back in the News. Don’t Let It Put Your Homeownership Plans on Hold.

Student loans are back in the spotlight. And whether you’ve been following the headlines closely or just catching bits and pieces here and there, there’s a good chance they’ve been on your mind lately.
And if you’re questioning whether you have to hit pause on your plans to buy a home, here’s the thing you have to remember:
Having student loans doesn’t automatically mean buying a home has to wait.
The Biggest Myth About Student Loans and Buying a Home
One of the most common misconceptions among first-time buyers is that they have to pay off their student loans before they can qualify for a mortgage. But in most cases, that’s just not true.
As an article from Redfin explains, student loans usually get evaluated the same way other debts do, like credit cards or car payments:
“Yes, you can get a mortgage with student loan debt. Lenders primarily assess your debt-to-income (DTI) ratio, which compares your monthly debt payments, including student loans, to your gross monthly income. Having student debt doesn’t automatically disqualify you if your DTI is within acceptable limits.”
So having that loan on your credit report isn’t some special red flag that immediately disqualifies you.
Instead, lenders look at your overall financial situation, including your income, credit history, and more. Student loans are one piece of that puzzle, but they’re not the entire picture.
You’re in Better Company Than You Think
Just to really drive this home, here’s a stat from the National Association of Realtors (NAR) that proves you can have student debt and still buy a home. Their research shows 33% of first-time homebuyers still had student loan debt.

That’s 1 out of every 3 first-time buyers. The median amount they owed? $30,400.
Let that reassure you that people are buying homes with student debt every day. And carrying student loans doesn’t automatically put homeownership out of reach.
Don’t Count Yourself Out Before You Even Try
At the end of the day, here’s where a lot of buyers trip themselves up. They assume the worst and never even check what they could actually qualify for. But your situation is more unique than a blanket “no.”
If your income is steady and the rest of your finances are in decent shape, buying a home could be more realistic than you think. The only way to know for sure is to actually run the numbers with someone who does this for a living.
You may discover you’re closer to buying than you think.
Bottom Line
Student loans don’t have to be the thing standing between you and owning a home. If you’ve been putting off your homebuying plans because of that debt, talk to a lender about your options. It may not be the barrier you think it is.
The 1 Factor That Explains Everything Happening with Home Prices Right Now
You’ve probably heard that home prices are cooling off. And that’s true – nationally. But zoom in on individual markets across the country, and the picture looks completely different depending on where you are.
Some areas are still seeing solid price growth. Others have gone flat. A few have actually dipped slightly negative. So, what’s causing all of that variation?
It All Comes Down to Inventory
Here’s the simple version:
- When there are more homes for sale, buyers have options.
- More options, means less competition.
- Less competition means sellers can’t push prices as high.
On the flip side, when inventory is tight, buyers are competing over a small pool of homes, and that pushes prices up.
That dynamic is playing out right now in a really visible way across the country.
Markets where inventory has climbed back to, or above, normal pre-pandemic levels are seeing prices flatten or fall slightly. Markets where inventory is still well below those 2019 benchmarks are still seeing prices rise. As Lance Lambert, CEO of ResiClub, puts it:
“Home prices are still climbing a little year-over-year in many regions where active inventory remains well below pre-pandemic 2019 levels, such as pockets of the Northeast and Midwest.
In contrast, some pockets in states like Texas, Florida, and Colorado — where active inventory exceeds pre-pandemic 2019 levels by a solid clip — are seeing modest home price pullbacks or flat pricing.”
The Maps Say It All
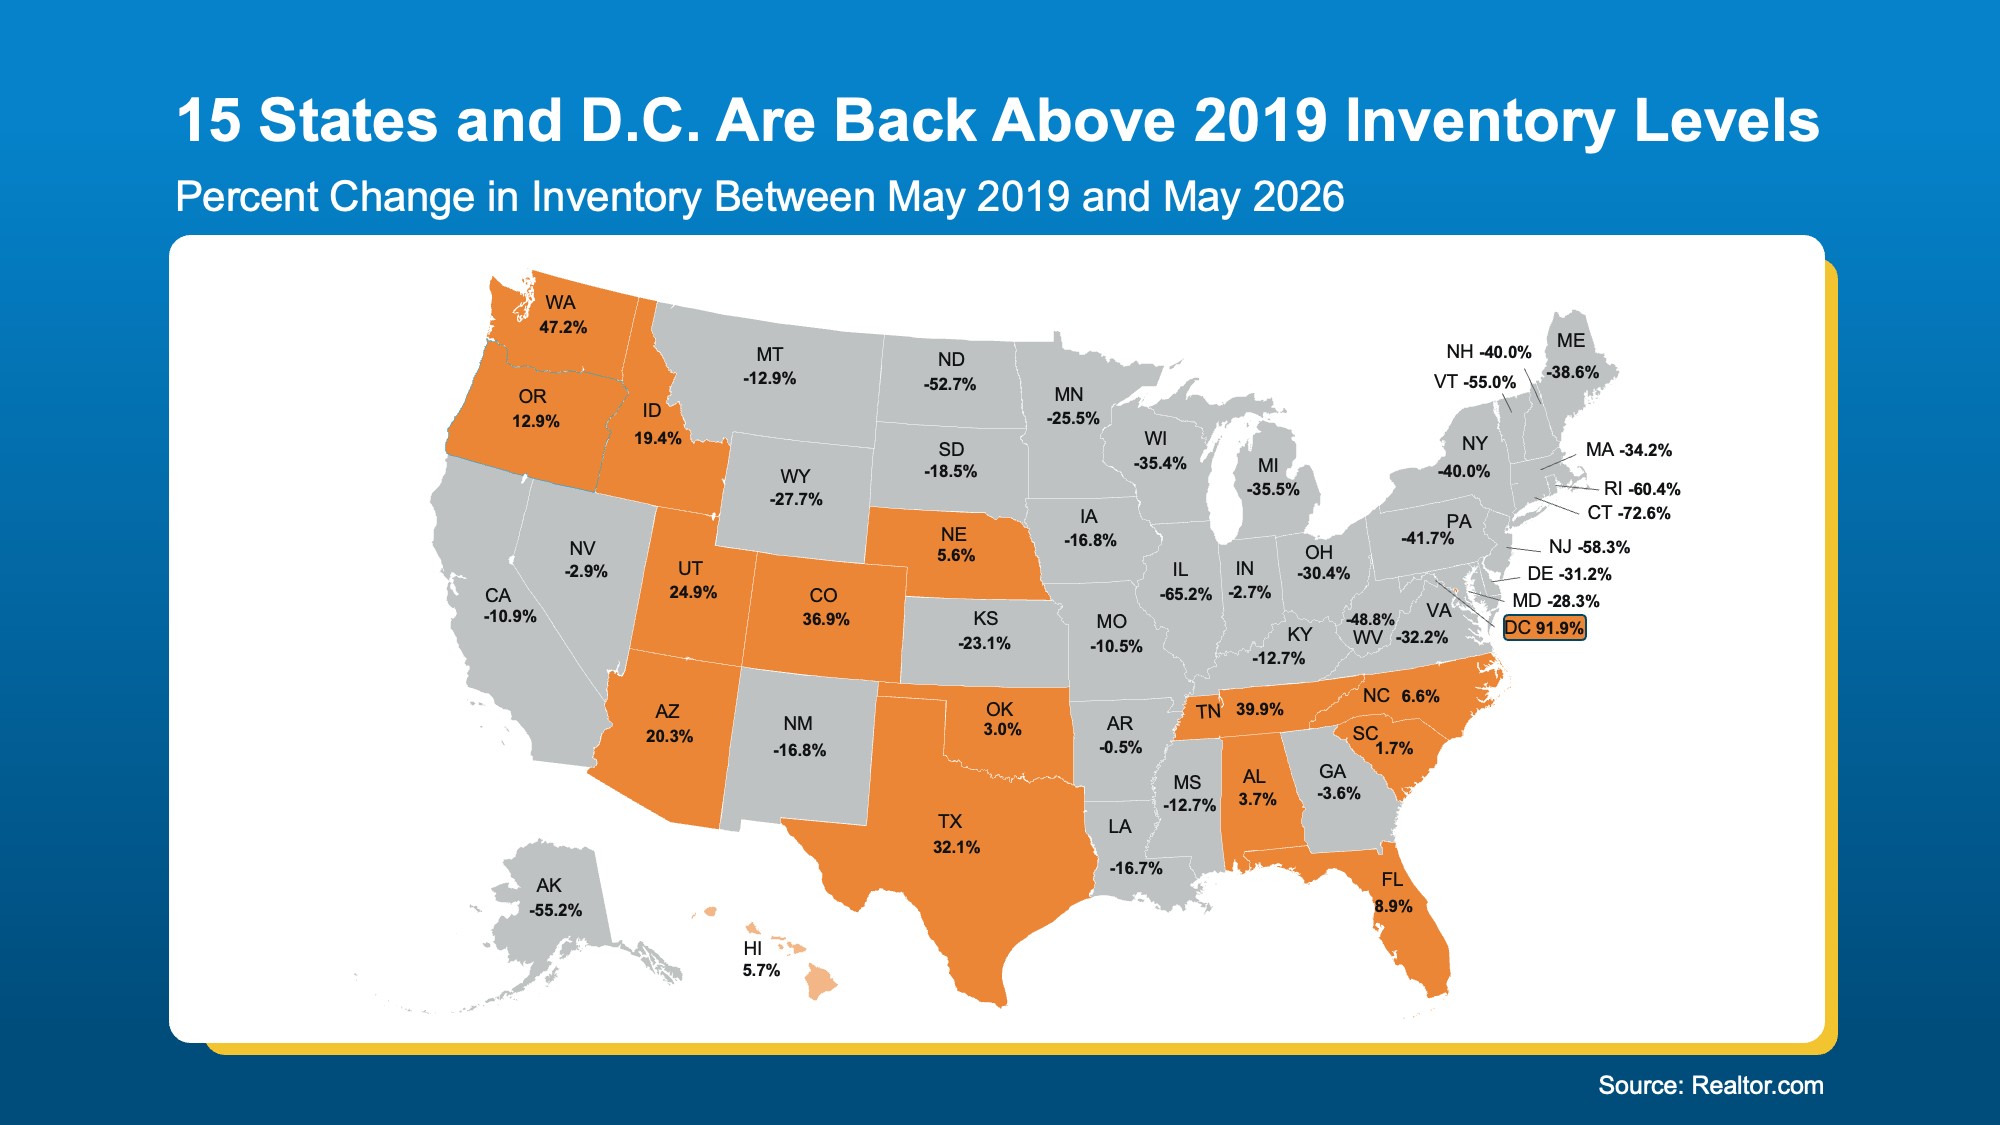
Take a look at where inventory stands today compared to 2019. In most places (the states in gray below), inventory still falls short of where we were back then. And that’s exactly why prices are climbing, albeit moderately, in the vast majority of states.
But you’re probably more interested in where prices are falling a bit, since that’s what is making headlines. So, let’s prove out how much inventory affects prices in those spots.
According to Realtor.com, 15 states and Washington, D.C. are now back above pre-pandemic inventory levels, and some by a wide margin (see the orange in the map below):
Now, let’s look at the latest Federal Housing Finance Agency (FHFA) data to see what’s happened to home prices in those same states over the past year (again, you’ll want to focus on the orange in the next map).
See how those line up pretty closely with the areas seeing more homes for sale today?
The overlap isn’t a coincidence. It’s cause and effect.
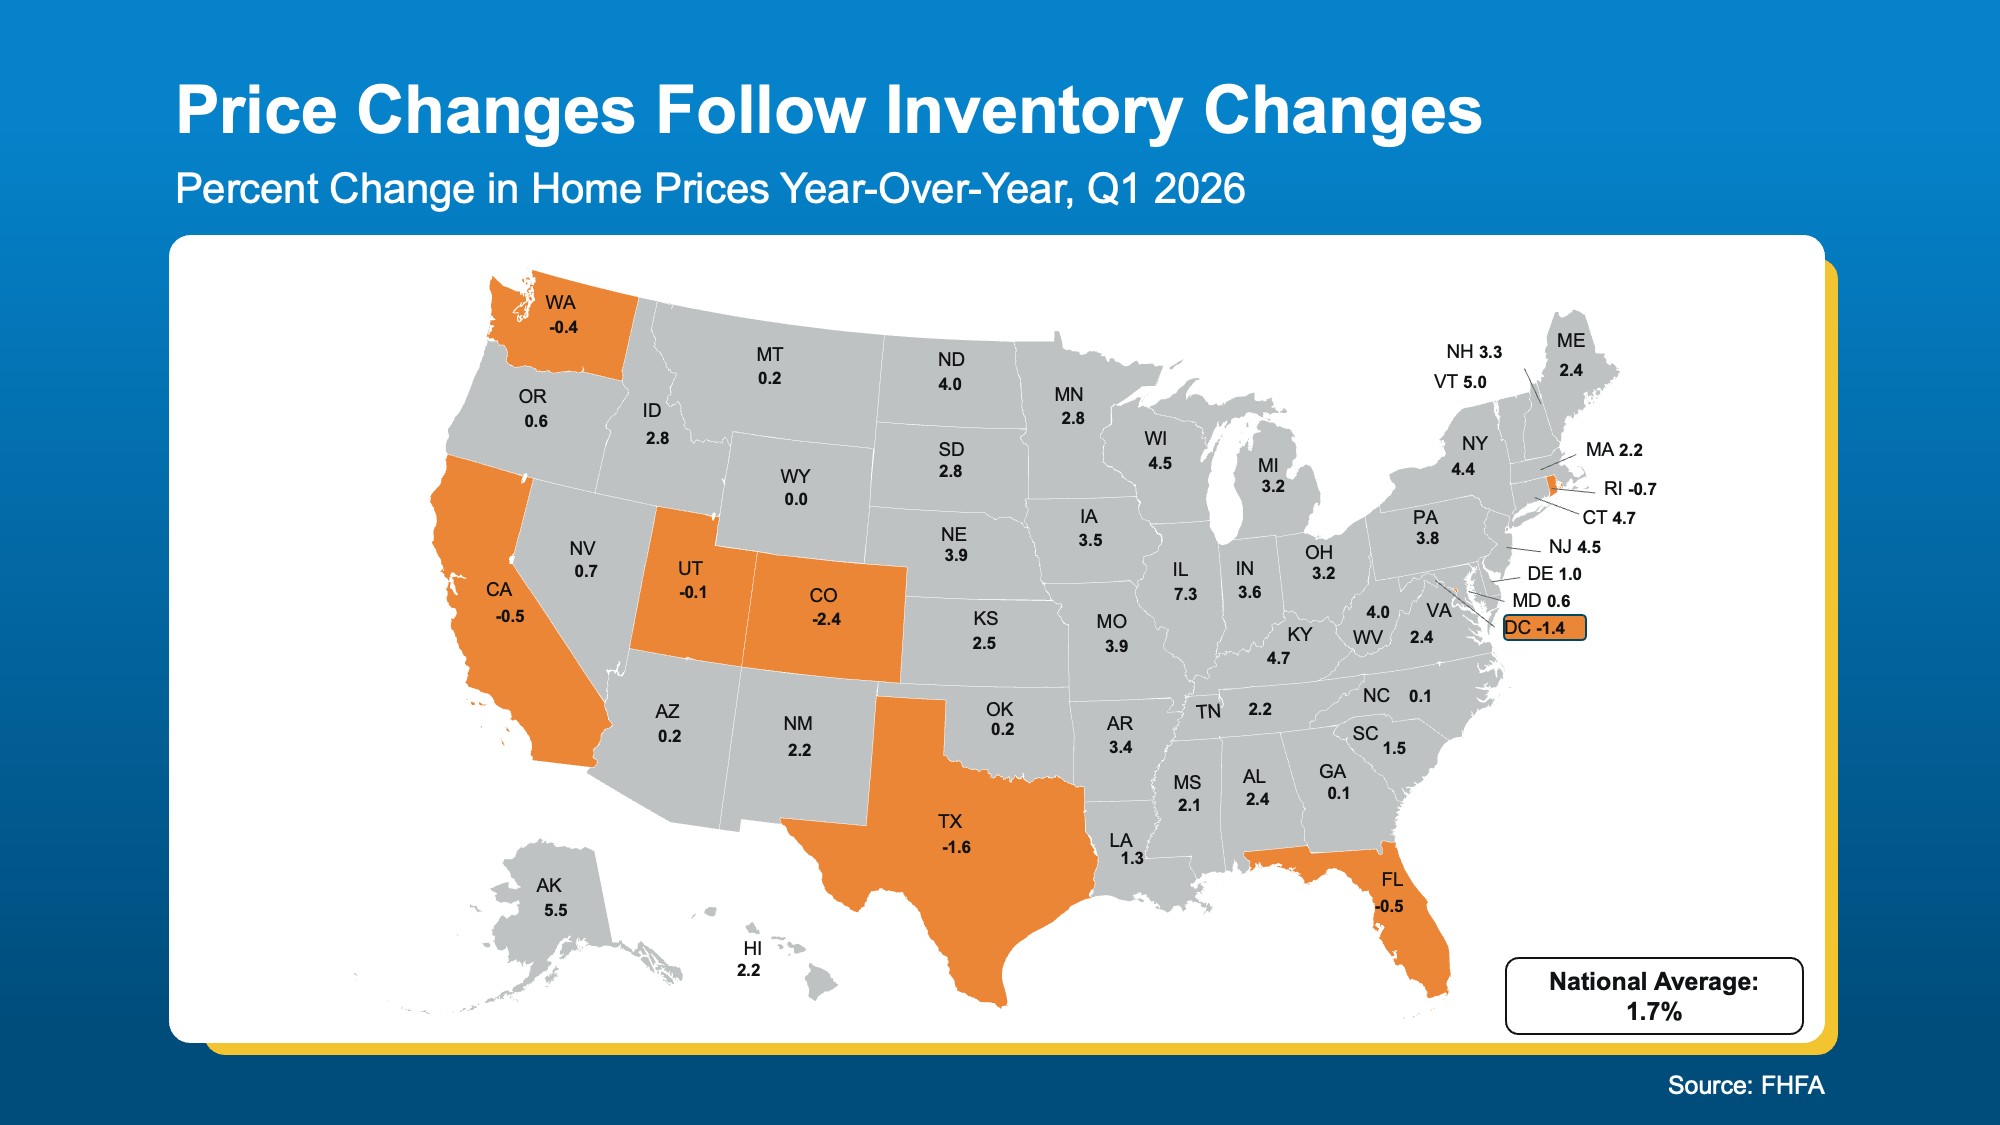
The national average of 1.7% price growth is accurate, but it’s an average of two very different stories happening at the same time – the few areas experiencing mild declines and the overwhelming majority that are still seeing prices rise.
What This Means If You’re Buying or Selling
If you’re a buyer, the market you’re shopping in matters a lot right now. In places like Texas, Colorado, or Florida, you may have real negotiating power – more choices, less competition, and sellers who are more motivated to make a deal. In tighter markets like much of the Northeast, you’re still likely facing a lot of competition.
If you’re a seller, pricing strategy is everything. In markets where inventory has risen, overpricing is one of the fastest ways to linger on the market and eventually sell for less than you would have with the right price from day one. In markets where inventory is still low, you’re in a strong spot, but getting your price right still matters if you want to attract serious buyers quickly. Either way, that’s where a local real estate agent earns their keep.
Bottom Line
When it comes to prices, where you are matters more than ever right now, and a local real estate agent is the best person to help you make sense of it.
Reach out today and let’s build a plan that fits our market.
The Real Reason Some People Are Still Moving Right Now
You may be telling yourself you’re going to wait to move – maybe you’re hoping mortgage rates will come down, prices will fall, or the market will feel a little easier.
And honestly? A lot of people feel that way right now. But here’s what some are starting to realize.
Waiting doesn’t usually fix the thing that made you want to move in the first place.
Your family still desperately needs more room. Your empty nest still feels too…empty.
Your parents or grandparents still need you to live closer.
You just got married… or divorced.
Your vision of retirement has you living somewhere else.
Eventually, life can reach a point where waiting feels harder than moving.
That’s why some people are still deciding to buy right now, even in today’s market. Not because conditions are perfect. But because the life changes behind their move never really went away.
And maybe that’s exactly where you are too. If so, you’re certainly not alone.
The Real Reasons People Move
Data from the National Association of Realtors (NAR) shows 1 in 5 buyers last year said they felt like they had to purchase a home at that time, no matter the market.
That’s an important reminder right now. Sure, the dollars and cents of your move have to make sense for you. But big life changes happen whether mortgage rates and home prices are high, low, or somewhere in between.
And those big life events happen more than you may think. NAR says roughly 22.5 million people experience major life changes in a typical two-year span (see graph below):
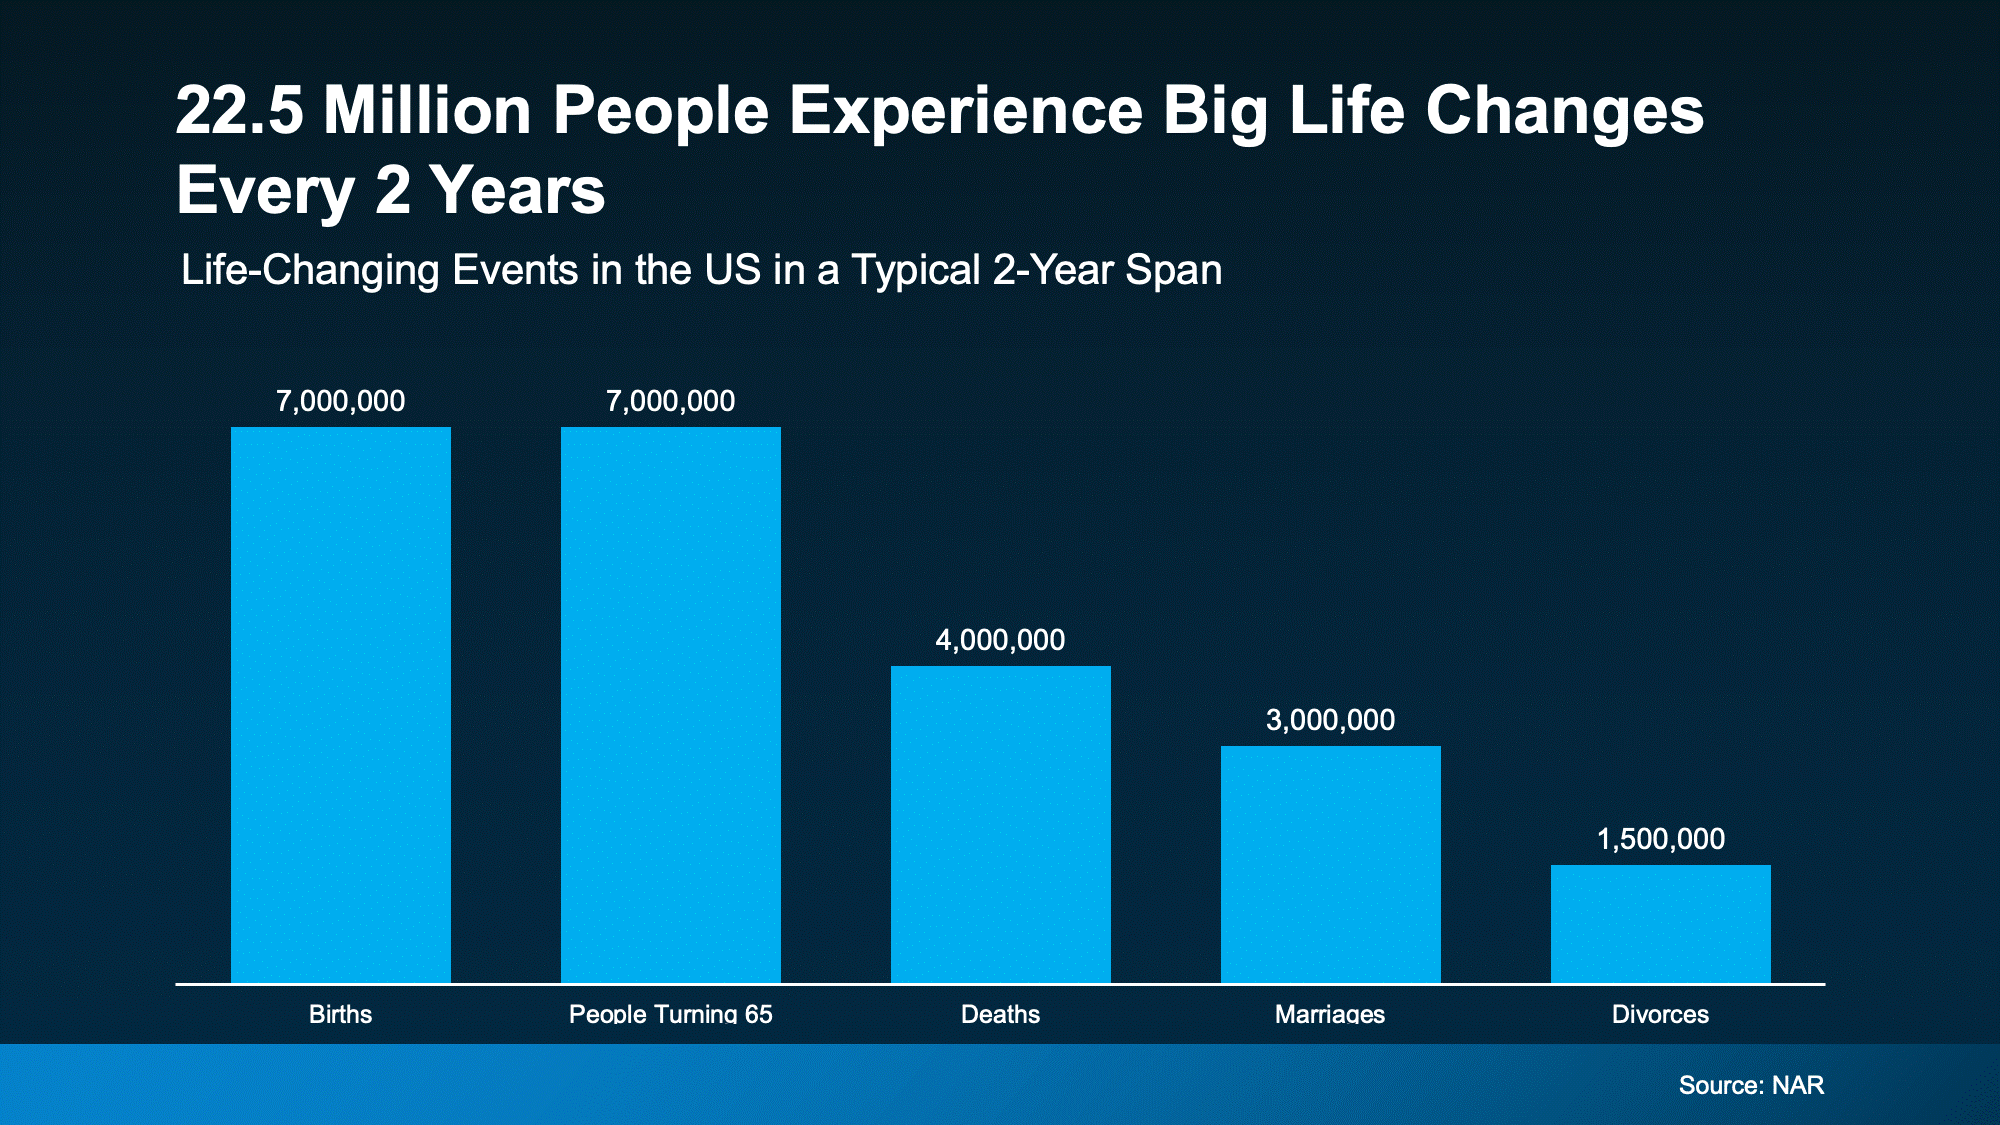
These are exactly the kinds of things that can change how much space you need, where you want to live, or what kind of lifestyle makes sense now. Chen Zhao, Head of Economics Research at Redfin, explains:
“Life doesn’t stand still—people get new jobs, grow their families, downsize after retirement, or simply want to live in a different neighborhood.”
And that’s what makes waiting so hard. Every month you spend hoping the market changes is another month living in a house that no longer works for your life. It’s stressful to feel stuck. And that feeling usually doesn’t disappear.
There May Be More Opportunity Than You Think
But while affordability is still a challenge, there may still be a way for you to make your move.
The number of homes for sale has been growing for 4 straight years (see graph below). That means more homes to choose from and, in some markets, more room to negotiate than buyers had just a few years ago.
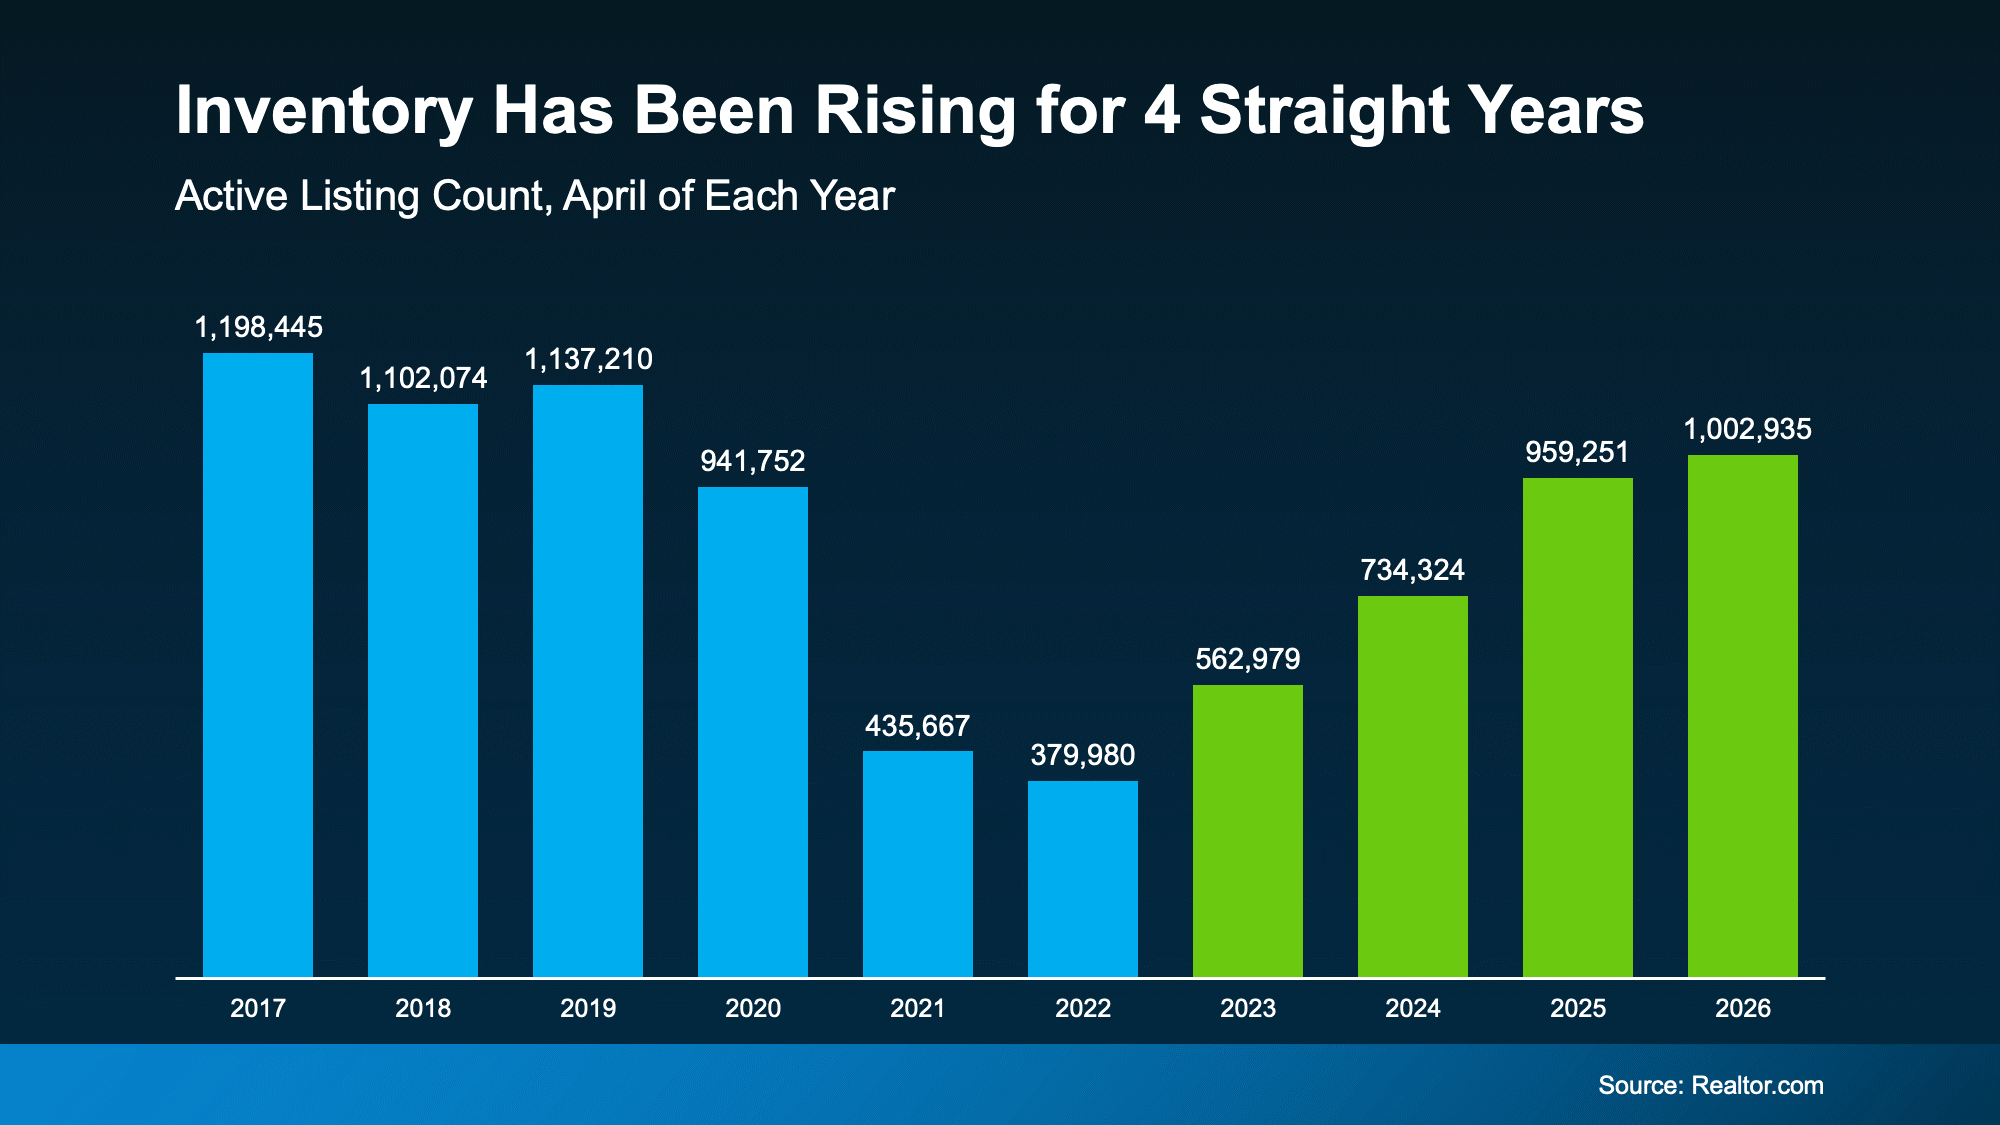
That doesn’t mean moving is suddenly easy. But it does mean some buyers are finding ways to make a move work. So, if you’ve been putting your plans on hold, maybe the question isn’t just:
“What’s the market doing?” or “When will it get better?”
Maybe ask yourself this, too: “Can I still live where I’m at right now and make it work?”
If the answer to that second question is “no,” it may be worth having a conversation about what your options look like today – despite where rates or prices are. You could find your move is still possible after all. With more homes for sale, there’s a better chance to find one that fits your life (and your budget) right now.
Bottom Line
Life changes. Priorities shift. Families grow. Kids move out. Careers evolve. And eventually, the house you’re in may stop fitting the life you’re living.
If that’s been weighing on you lately, let’s talk through what your options could realistically look like today, no matter where rates or prices are.
Life can’t always wait for perfect market conditions. Maybe you don’t have to either.
