Before rates crept back up, we actually had a few bright spots: pending sales jumped 19% from the prior month, and inventory dipped 2% — the first drop we’ve seen all year. That’s worth noting. But zoom out, and inventory is still up 45% year-over-year. Months of supply sits at 3.5, up 30% from last year. If we were cruising at 65 mph in 2025, we’re doing 39 mph now.
Pricing is down roughly 6% year-over-year — which puts us squarely back in 2023 territory. The peak pricing of early 2022 and most of 2024–2025? Unreachable for now. What that means practically: some sellers will net less than they paid, and it has a 2010 feel to it. The key difference is that most sellers today came in with real equity — this isn’t the sub-prime, zero-down era. That said, I’ve already seen a few short sales listed, and I expect more.
The elephant in the room: interest rates are at their highest since January 2025, and the Fed raised the Fed Funds rate for the first time since 2023. Layer in ongoing pressure on tech employment and general buyer hesitancy, and it’s a tough climate for sellers right now.
That said, the sky isn’t falling. It just feels that way. What we’re navigating is closer to a new normal than a freefall, and there is always a market. People will always need to sell, and people will always need to buy.
For sellers: Price war and beauty contest still applies. Prep the home well, price conservatively (meaning ahead of a declining market, so below current market value), and offset any real shortcomings — power lines, busy street, steep driveway, challenging layout — with perceived value. Depending on the issue, that might mean a 10% or so reduction. Don’t fight the market; get ahead of it.
For buyers: Same story: can you comfortably afford the monthly payment, and can you commit to 3–5+ years? If yes, this is your moment. Negotiate. You have leverage you haven’t had in years.
Now more than ever, both buyers and sellers need seasoned professionals in their corner.
Data centers probably weren’t on your list of things to think about when buying or selling a home.
School districts? Sure. How close you are to family? Absolutely. A large building full of computer servers down the road? Probably not.
But that may be changing.
Data centers are popping up in more communities across the country. And as they do, buyers and homeowners are starting to wonder what having one nearby could mean for everything from home values to utility bills. So, let’s get into what the data actually says. Because there’s a lot more nuance here than if they’re “good” or “bad.”
Data Centers Are Showing Up in a Lot More ZIP Codes
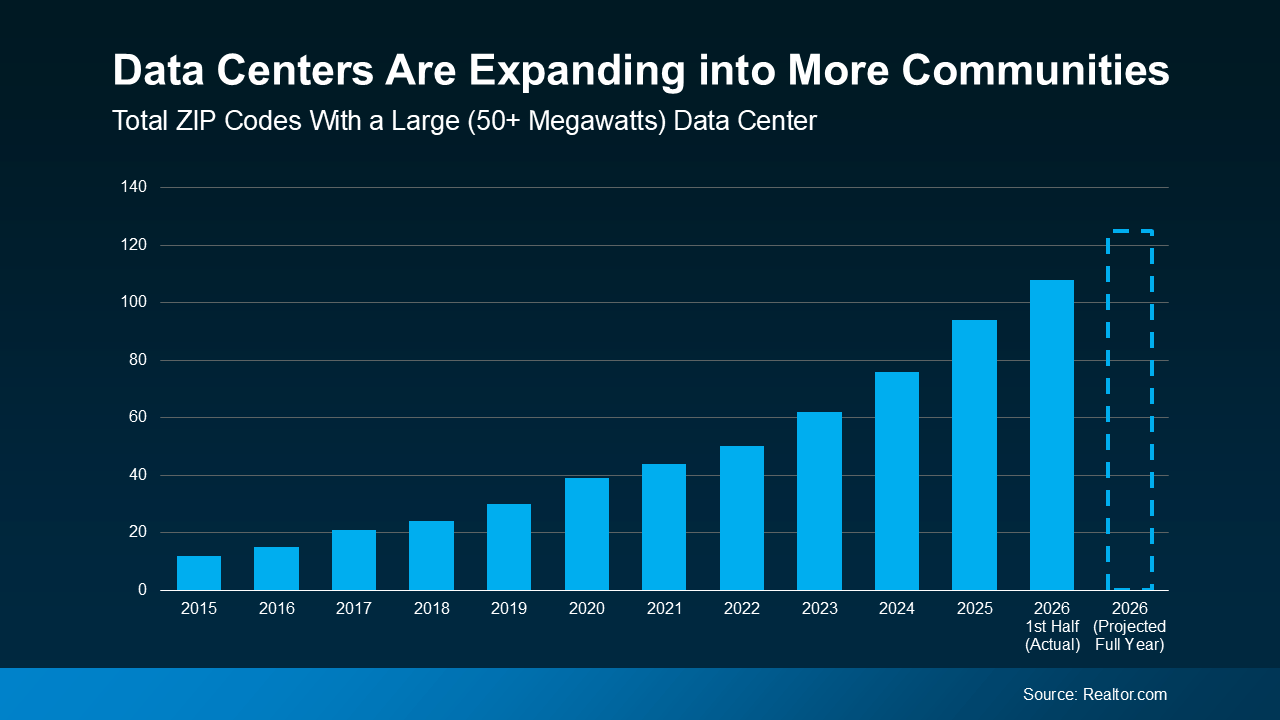
According to Realtor.com, back in 2015, only about a dozen ZIP codes had a large data center. But by the first half of 2026, that number had climbed to more than 100 – and it’s projected to rise even further by the end of the year (see graph below):
That’s a pretty dramatic increase in just over a decade. HousingWire shows a lot of that growth is in Texas, Virginia, Georgia, Pennsylvania, Ohio, Utah, Illinois, Arizona, Indiana, and Nevada.
And that ramp up explains why this is becoming a real estate conversation. More buyers are going to encounter a data center during their search. More homeowners are going to hear about one being proposed nearby.
And both groups are going to want to know what that could mean for them.
The Big Question: What About Home Values?
One of the first concerns homeowners and buyers may have is: could a nearby data center hurt home values? So far, there’s no evidence that says it automatically will.
Researchers compared communities that have large data centers to similar communities without them. A recent HousingWire article reports:
“. . . home values in data center ZIP codes generally tracked their matched communities — with no statistically meaningful gains or losses. Listing prices showed a modest initial increase around openings . . .”
That’s important context. Historically, simply having a data center nearby hasn’t been enough to send home values dramatically higher or lower.
That doesn’t mean every property will react the same way. Proximity, the surrounding development, and the specific facility can all matter. But for the typical homeowner or buyer, the data so far doesn’t point to an automatic impact on home values.
Living Near a Data Center Can Come with Tradeoffs
Like any major development coming to town, data centers can bring benefits along with things buyers and homeowners will want to consider.
On the plus side:
They may be part of a bigger growth story. A data center can usher in broader development in an area and substantial property tax revenue that can be used to improve the community.
Infrastructure may get an upgrade. New roads, fiber, power infrastructure, and other improvements can come along with major development.
They can generate economic activity. A data center can generate jobs which in turn fuels local housing demand and supports local businesses.
On the flip side:
They’re not exactly invisible. Large facilities, transmission lines, substations, and construction can change the look and feel of an area.
Noise can matter. Cooling equipment, generators, construction, and truck traffic may be noticeable depending on how close you are.
They use more resources. These facilities can require significant electricity and, depending on the cooling system, water. That can raise questions about local infrastructure and whether growing electricity demand could affect what residents pay.
On that last point, J.P. Blackwood, Public Affairs Liaison and Media Spokesperson for the Ohio Consumers’ Counsel (OCC), explained his take on what consumers need to know about data centers and their potential to impact utility costs to HousingWire:
“Utility rate increases tend to be gradual, and so that’s what I would expect here. Again, a number of factors can drive electricity prices higher and are driving them higher, and this is one of them. There are steps being taken around the country to mitigate the effects of data centers.”
Basically, they’re just one factor that can have an impact. And the key word there is “can” because it depends on where you live and what rules are in place in your area.
So, What Should Buyers and Homeowners Do?
If you’re buying, find out what’s already there – and what’s approved or proposed nearby. Consider the facility’s proximity, potential noise, future development, and whether utility costs are something you want to factor into your budget.
If you’re selling, don’t assume a nearby data center automatically hurts your home’s value. But buyers may have questions. Knowing the facts about the facility, construction timeline, noise, and future plans can help you address those concerns upfront.
Bottom Line
As more data centers pop up, they’re becoming another piece of the puzzle buyers and homeowners need to understand.
Have a data center nearby or one coming soon? Let’s talk about what it could mean for your home or your next move.
Lately, headlines have floated an eye-catching idea about tapping into your 401(k) to cover a down payment on a home. Maybe you’ve caught the buzz and wondered whether that money could get you into a home faster, especially with affordability as tough as it is.
Here’s what you need to remember. Pulling from your retirement savings is a big decision, so take time to weigh all your options first and be sure to talk with a financial expert before you do anything.
Why Dipping into a 401(k) Can Be Tempting
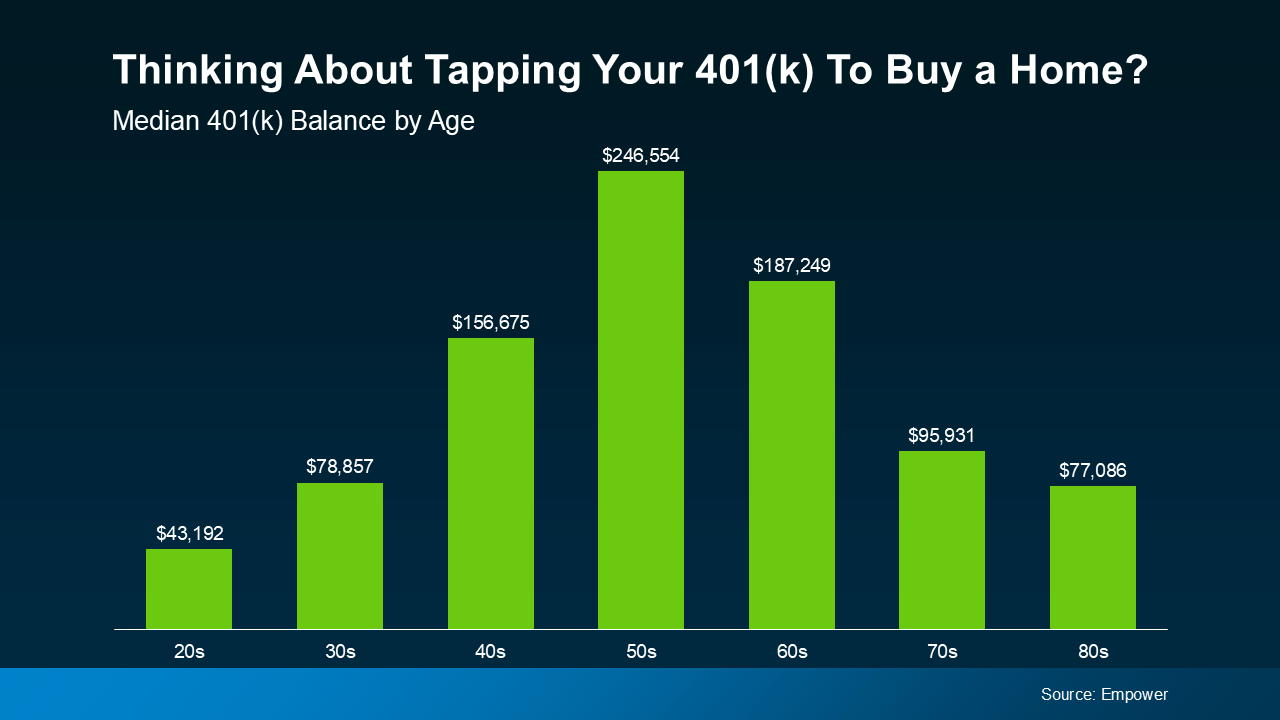
Data from Empower shows many Americans have built up considerable retirement savings. The median 401(k) amount for anyone in their 40s-60s is six figures(see graph below):
And when you’ve got a good chunk saved and your dream home is right there, reaching for it can feel like an easy call.
But dipping into your retirement savings to buy a home could cost you a penalty and set back your finances later on. That’s why it’s a good idea to explore other options for your down payment first. As Redfin says:
“If you’re struggling to save enough for a down payment, you may be wondering if tapping into your 401(k) is the right option. While it’s possible, doing so comes with significant risks, like early withdrawal penalties and lost investment growth.”
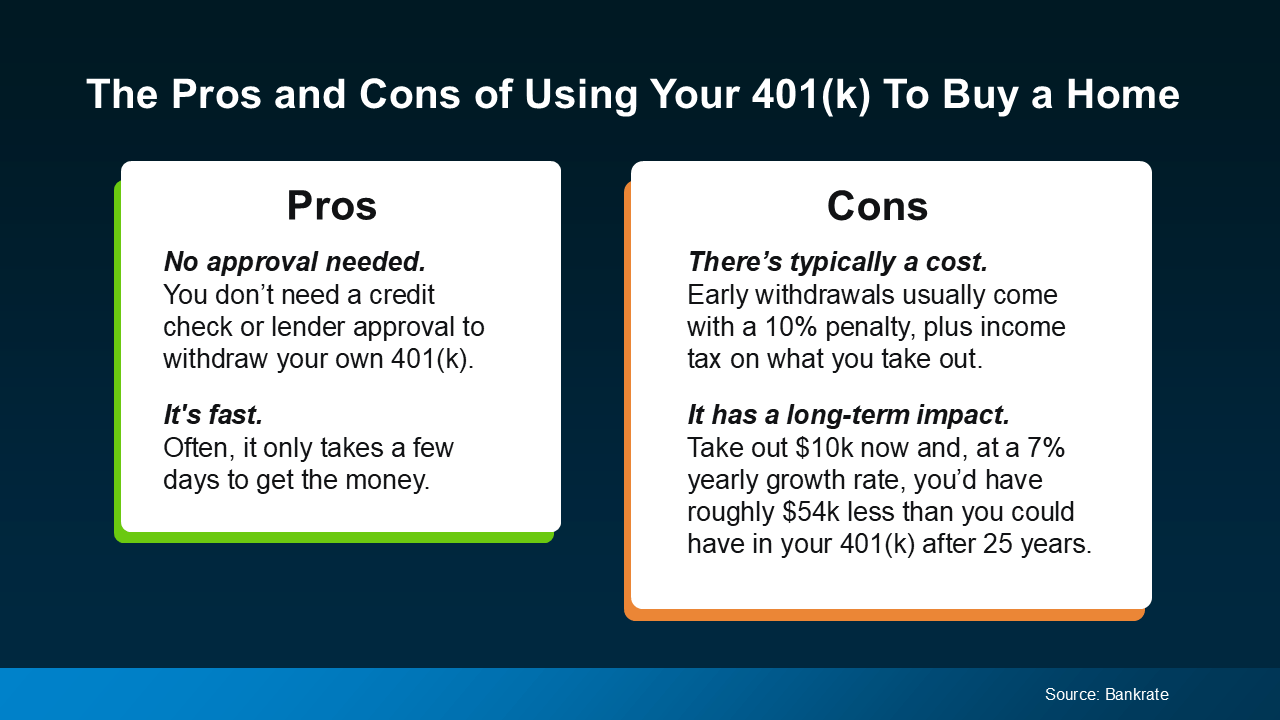
Before you decide, have a financial advisor help you compare the upsides to the risks. Bankrate points to a few of each (see visual): Other Options Worth Exploring First
Your 401(k) isn’t the only way to finance a home purchase. Redfin outlines a few other options to look into before you decide what to do:
Low and No-Down Payment Loans:FHA loans, for example, allow qualified buyers to put down as little as 3.5% of the home’s price, depending on their credit scores.
Down Payment Assistance Programs: Many national and local programs can help reduce what you pay toward your down payment or closing costs.
Make a Plan Before You Make a Move
No matter which route you take, talk with a financial expert first. The buyers who come out ahead build a solid plan with the right professionals before starting their journey to homeownership. As NerdWallet puts it:
“Even if you’re convinced a 401(k) loan is the way to go, it’s important to understand the risks at the outset.”
Bottom Line
Affordability is definitely a challenge, but that doesn’t mean tapping your 401(k) is your only way in if you want to buy.
If you’re considering using your 401(k) savings for a down payment, weigh all your options and talk with a trusted financial advisor before you make any decisions. They’ll help you make a plan to fit your goals and your budget.
You’re scrolling through listings on your phone and everything looks good until you see the price (or the estimated monthly payment). Then you close the app.
Because even if you love the house, the numbers feel impossible. But here’s the thing.
Nationally, there are more homes sitting on the market than there are people out there looking. And when sellers need buyers more than buyers need sellers, that shows up in the price.
Lower asking prices. More price cuts. And homes priced for what buyers can actually afford – not what sellers hope someone might pay.
And it may be enough to make buying more doable than you’d think.
4 Out of 10 Sellers Are Cutting Their Price
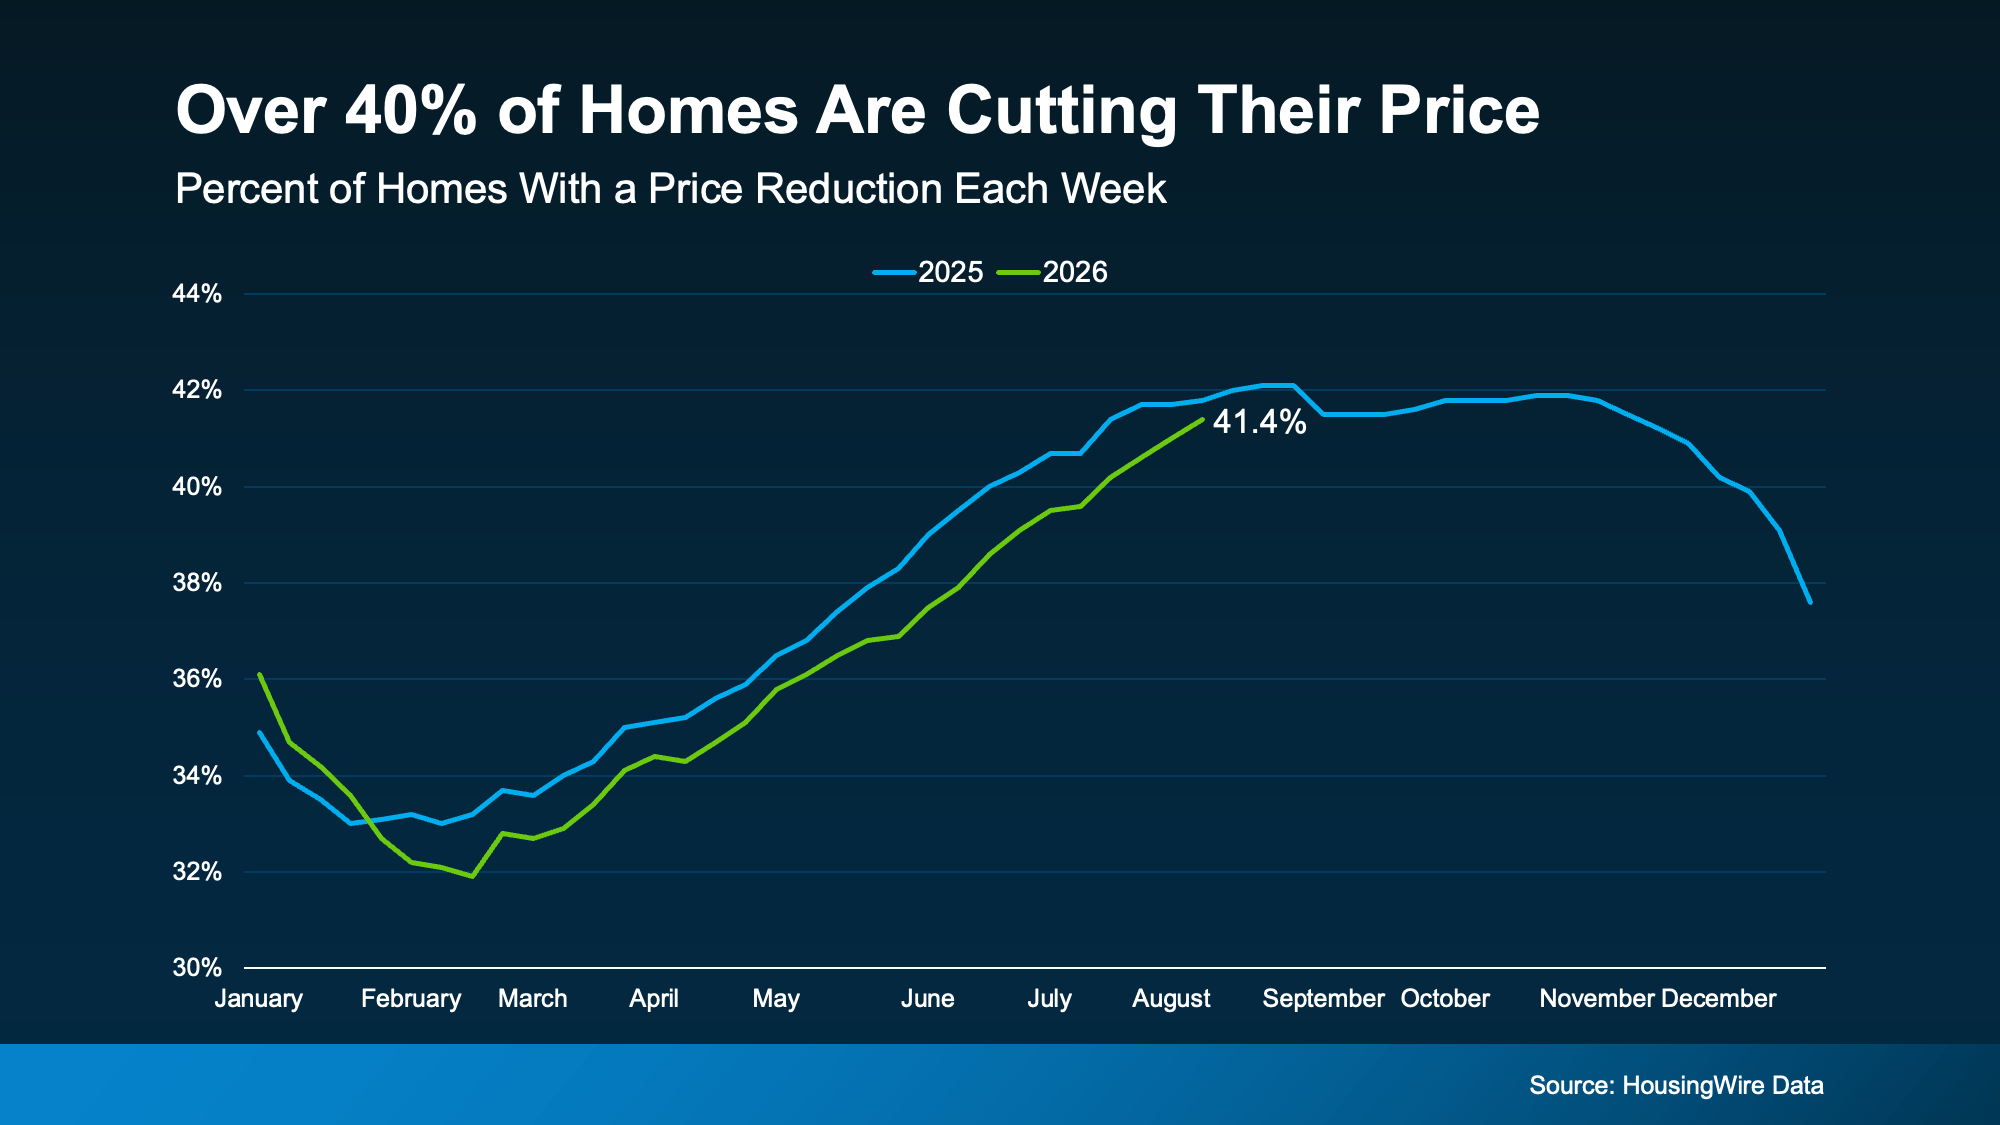
One of the clearest signs sellers are adjusting? Price cuts.HousingWireData shows more than 40% of sellers are dropping this price.
That’s just slightly behind the volume we saw last year (see graph below):
That’s more than 4 out of every 10 homes listed. Think about what that means. That’s thousands of sellers deciding they’d rather lower their asking price than keep waiting for someone willing to stretch their budget.
They know that to sell, they have to be willing to do some give and take. And when no buyers are biting, they’re pulling their biggest lever to draw buyers back in – their price. As Danielle Hale, Chief Economist at Realtor.com, explains:
“This is a market where people are adjusting and showing up rather than giving up. Sellers are meeting the market with more realistic asking prices, which is helping deals get done.”
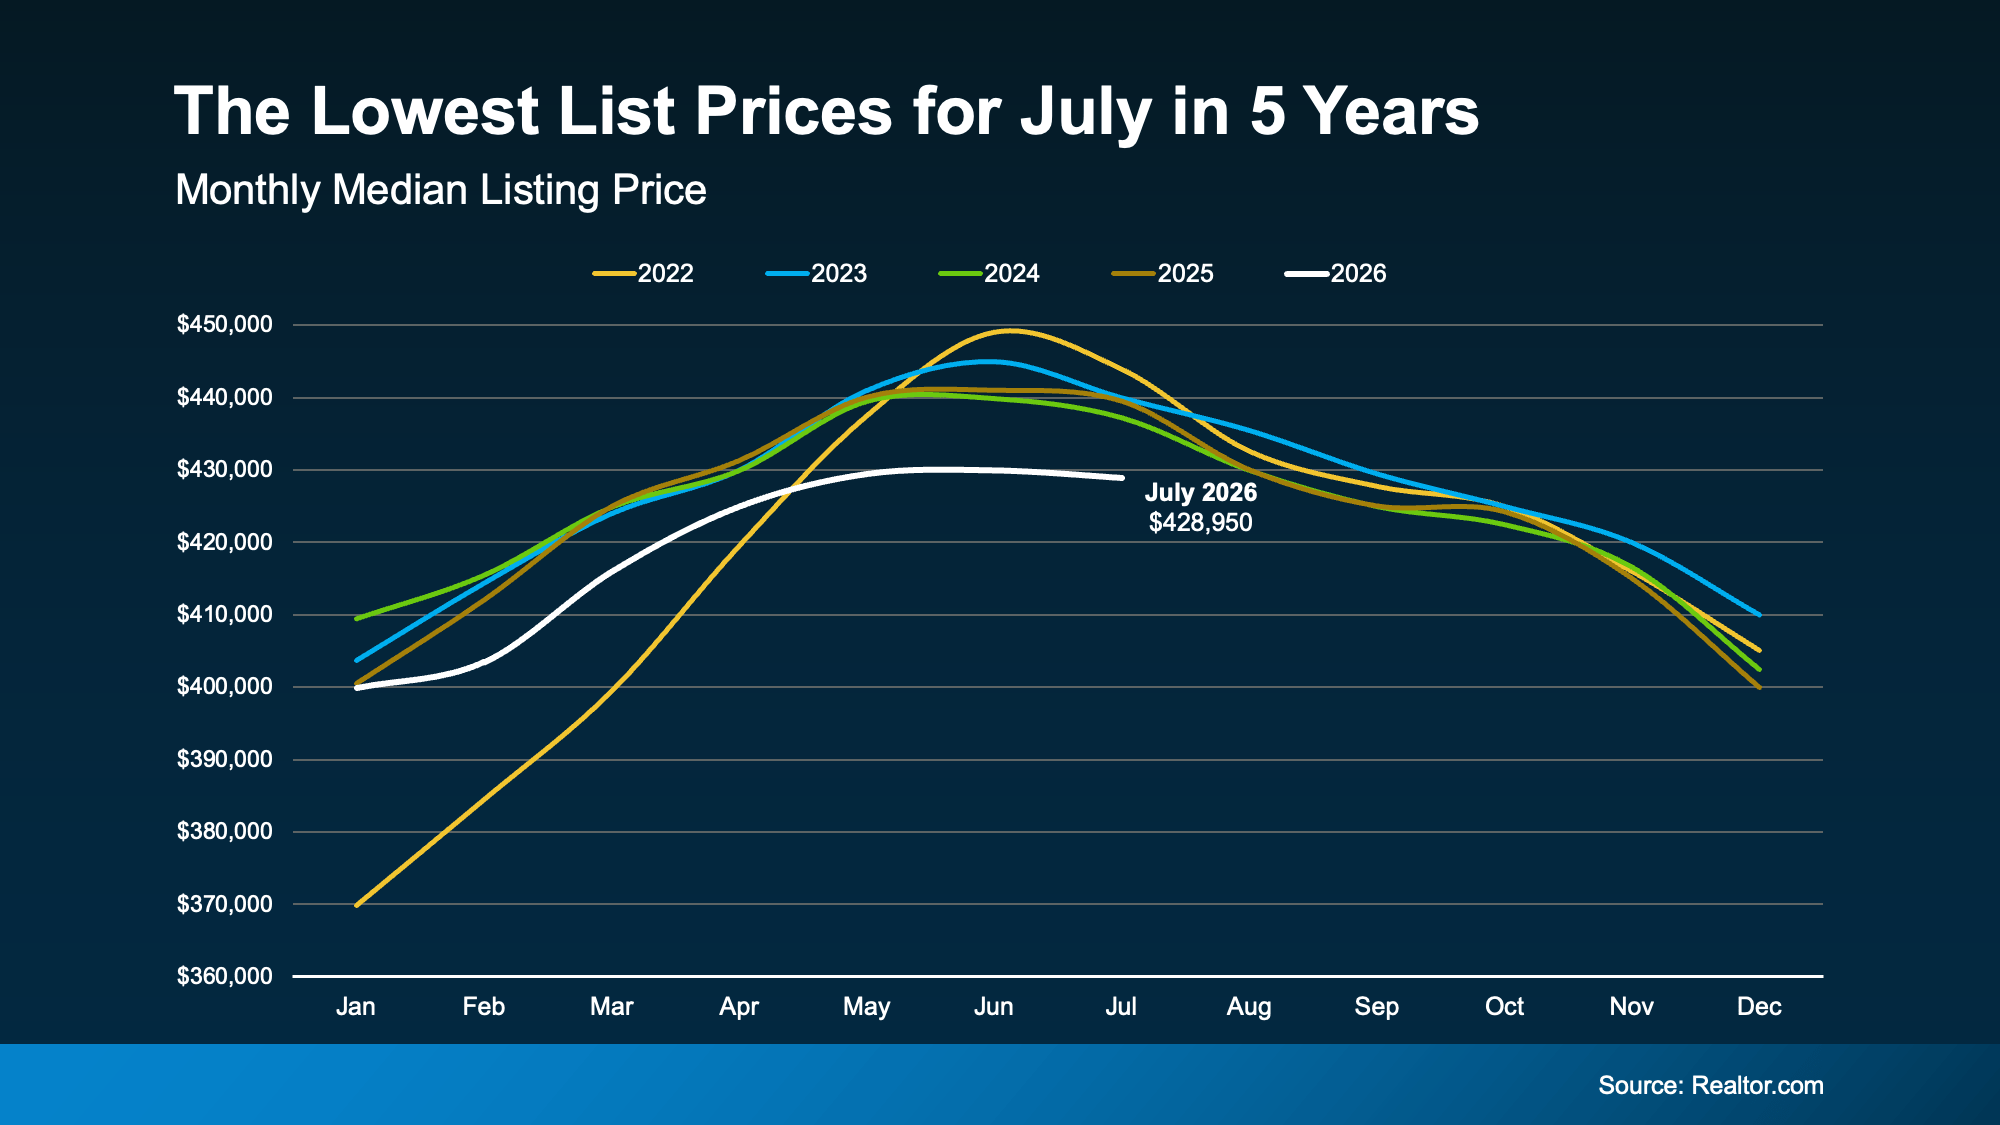
This July Saw the Lowest Median List Price for Any July in Five Years
What about the other 6 in 10 sellers? A lot of them started with a lower asking price to begin with rather than test the higher price and get crickets from buyers.
That may be why July 2026 had the lowest median list price of any July in the past five years, according to Realtor.com(see the white line in the graph below):
Now, that doesn’t mean home values are falling or that everything’s suddenly a steal. Prices are still above where they were before the pandemic. But what it does mean is this.
Sellers no longer banking on bidding wars or expecting buyers to pay whatever they ask. Instead, many are listing at prices that better reflect today’s market from the very beginning.
And honestly, whether they’re pricing competitively from day one or adjusting after a few weeks on the market, the message for you is the same:
Sellers are more willing to meet you where you’re at.
Because in many markets throughout the country, you’re not fighting over a house anymore. Sellers are fighting over you. And that’s information you can use to get a better deal.
Yes, affordability can be a real challenge. And the monthly payment you take on definitely does matter. But if you’ve been assuming everything is out of budget, there may be more wiggle room than you think.
Bottom Line
Right now, sellers are flexible on the price in ways they weren’t before. Let’s take advantage of that flexibility.
You may be surprised by what’s available – and how willing today’s sellers are to work with buyers.
Four months of inventory. Let that sink in. We are teetering on the edge of a buyers’ market — territory the Eastside hasn’t seen since around 2012. This is uncharted water. But uncharted doesn’t mean dangerous. It means you need a good navigator.
Let’s start with what the data is actually telling us. The median sold price came in at $1.575M — essentially flat, both month-over-month and year-over-year. After last month’s small uptick, that’s a stabilizing signal, not a collapse. Inventory is up 40%, pendings are down 8%, so buyers are buying. The market isn’t frozen. It’s just different.
Rates are sitting at 6.69%, and I keep hearing people clutch their pearls over it. Rates aren’t going anywhere meaningful anytime soon. The latest prediction I saw had rates dropping to 6.2% eventually — and that’s simply not worth putting your life on hold for. If you’re sitting on a sub-5% rate, yes, today’s rates sting. I get it. But focus on the payment, keep the home, and you’ll be fine.
Here’s the number that tells the real story: only 27% of homes sold at or above asking price, and that is likely after a 5% price drop to cancel and relist. That means three out of four are closing below list — sometimes well below. When that’s the reality, the strategy has to shift.
For sellers: the comps conversation has changed. Closed sales tell you where the market was. Active listings tell you what buyers are choosing between today. Pending sales tell you what buyers are actually willing to buy. When I sit down to recommend a list price, I’m spending more time on actives and pendings than I am on solds. Your competition isn’t a sale from four months ago — it’s the home two streets over that just listed yesterday.
For buyers: this is genuinely one of the best environments in over a decade to be a buyer on the Eastside. More choices, motivated sellers, and real room to negotiate. That said, don’t mistake a buyers’ market for a slow market — homes that are priced right and show well are still moving. Show up ready.
Lastly, as I type this update, it appears the market might be leveling out. I think prices have settled and a little balance is coming into play, but, as always, time will tell.


 Facebook
 X
 Pinterest
 Copy Link